Getting access to capital is not always about keeping a business afloat. Sometimes, your business is doing well you have customers, sales and opportunities but your cash flow simply cannot move as quickly as your growth plans. Maybe a major customer has not paid an invoice yet. Maybe you need to purchase inventory before your next sales cycle. Maybe a large order has landed but fulfilling it requires cash up front. Or perhaps you want to invest more in marketing while your revenue is growing.
For UAE SMEs, the real question is not simply “Where can I get business financing?”
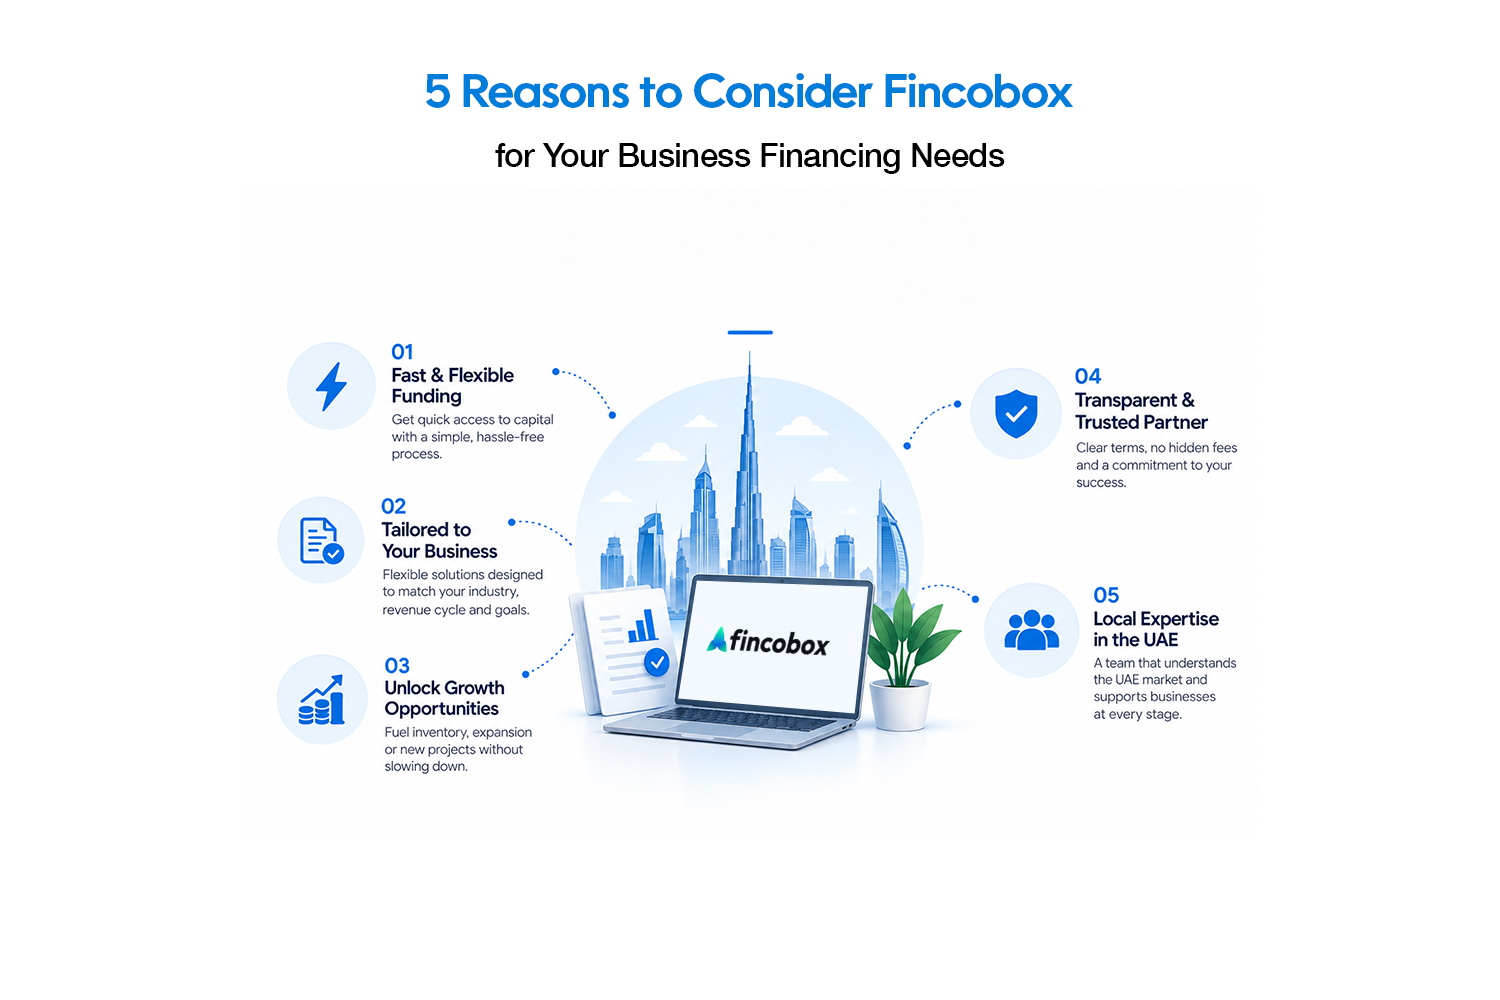
It is: “Which financing solution actually fits the way my business operates?” Here are five reasons businesses may consider Fincobox for their financing needs.
1. You Can Choose Financing Based on Your Business Need
Not every cash-flow problem is the same. A business waiting 60 days for a customer to pay has a very different financing requirement from an e-commerce company that needs additional inventory or a distributor trying to fulfil a large purchase order.
Fincobox takes a use-case-first approach with four main liquidity solutions:
- Invoice Discounting – for eligible businesses with outstanding invoices
- Revenue-Based Liquidity – for businesses with consistent revenue
- Short-Term Working Capital – for operational liquidity requirements
- Purchase Order Liquidity – for eligible businesses that need funding to fulfil purchase orders
That distinction matters. Instead of starting with a generic loan amount, businesses can first identify what is creating the cash-flow gap and then explore the financing option that corresponds to it.
Which Fincobox solution could fit your situation?
| Your business situation | Potential Fincobox solution |
| Cash is tied up in unpaid invoices | Invoice Discounting |
| Consistent revenue and a growth opportunity | Revenue-Based Liquidity |
| Temporary operating cash requirement | Short-Term Working Capital |
| Large order requiring upfront fulfilment costs | Purchase Order Liquidity |
The appropriate product, eligibility and terms will depend on the individual business and assessment.
2. Fincobox Financing Is Non-Dilutive
For many founders, getting capital creates another concern:
“How much of my business do I have to give away?”
With equity financing, raising capital means giving investors an ownership stake in the company. Fincobox takes a different approach. Its liquidity solutions are positioned as non-dilutive, meaning eligible businesses can access financing without selling equity or giving up ownership of their company. This can be particularly relevant for founders who want to maintain control while accessing working capital for growth. For example, a growing D2C brand may want additional capital to increase inventory or marketing spend without bringing an investor into the business simply to fund a short-term requirement.
However, non-dilutive does not mean cost-free. Businesses should always review the applicable financing costs, fees, repayment or settlement mechanics and contractual terms before accepting an offer.
3. It Is Built Around UAE SME Cash-Flow Challenges
Business financing should make sense for the market it serves. Fincobox is focused on UAE SMEs, with solutions designed around common working-capital situations such as unpaid invoices, growing revenue, purchase orders and short-term operational requirements. This is particularly relevant as UAE SMEs continue to focus heavily on growth. According to Mastercard’s 2026 SME Confidence Index, 83% of UAE SMEs surveyed reported revenue growth over the previous 12 months, while 50% said they were seeking access to credit to support growth. That highlights an important point: Businesses do not always need financing because they are struggling. Sometimes they need financing because they have an opportunity to grow faster than their available cash allows.
4. You Can Unlock Working Capital Without Waiting for the Entire Cash Cycle
Cash flow timing can create a frustrating situation for a growing business.
You make the sale today.
You deliver the product or service.
You issue the invoice.
And then you wait.
If your customer pays after 30, 60 or 90 days, the cash generated by that sale is temporarily unavailable for your next business requirement. Fincobox’s Invoice Discounting solution is designed to help eligible businesses unlock liquidity against qualifying invoices. Fincobox states that eligible businesses can access up to 90% of invoice value, subject to assessment and applicable terms.
For a business with significant receivables, this can potentially turn outstanding invoices into usable working capital sooner. That capital could then be used for business needs such as:
- Paying suppliers
- Purchasing inventory
- Managing operating expenses
- Fulfilling new orders
- Supporting expansion
The key is that invoice discounting addresses a timing problem: money has already been earned but has not yet been collected.
5. Fincobox Gives Growing Businesses More Than One Financing Route
Your business will not have the same financing requirement at every stage. Today, your biggest issue might be unpaid invoices. Next quarter, you might need capital to purchase inventory. Later, a major customer order could create a need for purchase-order liquidity. That is why having access to different financing solutions can be valuable. Fincobox offers multiple liquidity products within one platform, including invoice discounting, revenue-based liquidity, short-term working capital and purchase order liquidity. For a growing UAE SME, this creates an opportunity to think about financing according to the cash-flow event, rather than treating every requirement as a traditional business loan.
What Makes Fincobox Different From Traditional Business Financing?
Traditional financing can still be appropriate for many businesses. But it may not always match the timing or structure of a particular working-capital requirement. Fincobox focuses on liquidity solutions connected to specific business circumstances.
For example:
Unpaid invoice → Invoice Discounting
Consistent revenue → Revenue-Based Liquidity
Large purchase order → Purchase Order Liquidity
Short-term cash requirement → Working Capital
This approach can make the financing conversation more practical:
What does your business need the money for?
rather than simply:
How much money do you want to borrow?
Who Should Consider Fincobox?
Fincobox may be worth exploring if you are a UAE SME that:
- Has a clear working-capital requirement
- Has outstanding eligible invoices
- Generates consistent revenue
- Needs capital to support growth
- Has received a qualifying purchase order
- Wants non-dilutive financing
- Needs a financing solution aligned with a specific cash-flow situation
Eligibility is not automatic. Businesses are assessed based on the relevant product, business information, financial performance and applicable criteria.
What Should You Check Before Choosing Fincobox?
Choosing a financing provider should never be based on speed or convenience alone. Before accepting any financing offer, understand:
1. The total cost
Know what the financing will cost your business.
2. The repayment or settlement structure
Understand exactly how and when the facility needs to be settled.
3. The financing period
Make sure the duration matches your actual cash-flow cycle.
4. The funding purpose
Be clear about what the capital will achieve.
5. Your ability to repay
Consider what happens if sales are lower or customer payments are delayed Fincobox itself notes that businesses should understand total financing costs and repayment or settlement mechanics when evaluating digital-first financing.
Final Thoughts
The best business financing is not necessarily the financing with the biggest limit or the quickest application. It is the financing that fits the problem your business is actually trying to solve. For one UAE SME, that might mean unlocking cash from unpaid invoices. For another, it could mean funding inventory based on consistent revenue. For another, it could mean fulfilling a large purchase order without putting pressure on existing cash reserves. Fincobox gives eligible UAE SMEs access to multiple non-dilutive business financing solutions, allowing businesses to explore different ways of addressing working-capital and growth requirements. If your business has a specific cash-flow requirement, the first step is simple: Identify the gap. Understand the cost. Choose the financing structure that fits.
Frequently Asked Questions
1. What is Fincobox?
Fincobox is a UAE-focused digital financing platform that provides non-dilutive liquidity solutions for eligible SMEs, including invoice discounting, revenue-based liquidity, short-term working capital and purchase order liquidity.
2. What types of business financing does Fincobox offer?
Fincobox currently lists four key liquidity solutions: Invoice Discounting, Revenue-Based Liquidity, Short-Term Working Capital and Purchase Order Liquidity.
3. Is Fincobox financing available to UAE SMEs?
Yes. Fincobox is specifically focused on providing liquidity solutions to UAE SMEs. Eligibility depends on the business, financing product and assessment criteria.
4. Does Fincobox require businesses to give up equity?
Fincobox describes its liquidity solutions as non-dilutive, meaning businesses do not need to sell equity or ownership to access the financing.
5. How much can I get through Fincobox?
The available financing amount depends on the business, product and credit assessment. Fincobox’s website currently displays an estimated overall credit range of AED 50,000 to AED 2 million, while noting that final limits depend on credit evaluation.
6. Can Fincobox help if my cash is stuck in unpaid invoices?
Yes. Fincobox offers Invoice Discounting for eligible businesses and states that businesses can access up to 90% of eligible invoice value, subject to assessment and applicable terms.
7. Is Fincobox suitable for growing businesses?
It can be, particularly where a business has a defined working-capital or growth requirement. Fincobox offers different liquidity solutions for situations including consistent revenue, unpaid invoices, purchase orders and short-term working-capital needs.
8. What should I consider before applying for Fincobox financing?
Consider your exact funding requirement, total financing cost, applicable fees, repayment or settlement structure, financing period and ability to meet the obligations. Financing should support a clear business objective rather than simply increase available cash.
Leave a Reply