Category: Uncategorized

  • How Fincobox Helped an IT Infrastructure Business Manage Working Capital for Growth

    How Fincobox Helped an IT Infrastructure Business Manage Working Capital for Growth

    For an IT infrastructure business, winning a project is only one part of the equation. Before a customer payment reaches the bank account, the business may need to purchase networking equipment, switches, security systems and other technology products, while also covering installation, logistics and project execution costs. When several projects run simultaneously, the gap between supplier payments and customer collections can become a significant working-capital challenge. This was the situation faced by a Dubai-based IT infrastructure and technology solutions business that approached Fincobox for additional working capital to support its growing project pipeline. The case provides a practical look at how project-based technology businesses can manage cash flow, procurement and growth through the right financing strategy. 

    The Business Behind the Case 

    The business operates in the B2B technology sector, providing IT infrastructure products together with installation and implementation services. Its solutions include: 

    • Networking infrastructure 
    • Switching equipment 
    • Wireless systems 
    • CCTV and security solutions 
    • Access-control systems 
    • Structured cabling 
    • Installation and implementation services 

    Rather than selling individual products in isolation, the company typically delivers complete project solutions. A single customer project might combine networking equipment, switches, routers, cabling and security products along with installation services. This project-based model means that the company’s financing needs are closely connected to the timing of its projects. The business serves approximately 40–50 customers, including enterprises, schools, logistics companies, agencies and other corporate customers. Individual invoices can range from approximately AED 100,000 to AED 1 million, depending on the project. Pasted text 

    Why Growth Can Create a Cash-Flow Problem 

    A growing order book is usually good news. But for businesses that need to procure products before completing a project, growth can also increase the amount of cash required upfront.The business needs cash during the middle of this cycle, while a significant portion of its revenue arrives later. 

    In this case, customer payment terms generally ranged from 30 to 60 days. At the same time, suppliers had different payment requirements. Some offered credit, while others required upfront payments or arrangements such as 50/50 payments. Pasted text This creates a classic working-capital gap. The business may have confirmed work and reliable customers, but still need additional liquidity to pay suppliers and procure equipment before the customer settles the invoice. 

    The Impact of Project-Based Procurement 

    One of the most important characteristics of this business was its procurement model. Products were primarily sourced through UAE-based distributors and purchased according to project requirements rather than being held as large amounts of general inventory. The company estimated its current inventory at approximately AED 300,000, with typical inventory or project holding periods of around 45–60 days. Pasted text. This is important because inventory does not necessarily mean excess stock. For project-based businesses, inventory can represent money temporarily tied up in equipment that is waiting to be installed, delivered or handed over. The longer the project cycle, the longer that capital can remain unavailable for the next project. 

    A Growing Business With a Clear Funding Requirement 

    The business had historically generated approximately AED 7–8 million in annual turnover, with previous-year revenue of around AED 8 million. At the time of the assessment, management indicated that current-year revenue had reached approximately AED 6 million, with an expectation of reaching approximately AED 10 million for the year. The company was also seeing increased project activity and expected business levels to improve as recently secured projects were executed. Pasted text However, higher activity meant higher funding requirements. Management identified an additional working-capital requirement of approximately AED 700,000–1 million, primarily for: 

    • Supplier and vendor payments 
    • Procurement of IT products 
    • Project-related working capital 
    • Managing multiple projects simultaneously 

    The company was also open to beginning with a smaller facility and increasing it later based on business requirements and repayment performance. Pasted text 

    An Important Cost Pressure: Logistics 

    The financing requirement was not driven only by project volume. The business was also experiencing increased logistics costs, particularly for products sourced from international markets. Management highlighted a significant increase in container costs for shipments from China to Dubai, with costs reportedly rising from approximately USD 6,000–8,000 historically to around USD 20,000. Higher logistics expenses were putting additional pressure on both margins and working capital. Pasted text. For an importer or technology reseller, this is an important consideration. Even when the selling price of a product remains unchanged, an increase in freight and logistics costs can mean more cash is required before the business receives payment from its customer. 

    How Fincobox Approached the Requirement 

    Fincobox looked at the funding requirement in the context of the company’s entire operating cycle. Instead of treating the request simply as a requirement for AED 700,000–1 million, the assessment considered how money moved through the business: 

    Customer Order 

    ↓ 

    Advance / Customer Payment 

    ↓ 

    Supplier Procurement 

    ↓ 

    Equipment & Logistics 

    ↓ 

    Installation 

    ↓ 

    Project Completion 

    ↓ 

    Customer Collection 

    Understanding this cycle is essential when determining the appropriate financing structure. The objective was to identify financing that could help the business manage the timing difference between when it needed to pay for a project and when it expected to receive the corresponding customer collections. 

    Why Existing Financing Does Not Always Solve Future Funding Needs 

    The business already had financing facilities that had been used for project cash-flow support. It also had an existing alternative funding arrangement with an available limit of approximately AED 250,000. 

    However, its working-capital requirement had increased as project activity expanded. This highlights an important point for growing SMEs: Existing financing capacity should not automatically be assumed to be sufficient for future growth. As revenue increases, procurement volumes can increase as well. A business that once required AED 300,000 of working capital may eventually need significantly more to execute multiple projects simultaneously. The right approach is to periodically reassess the financing requirement against the current project pipeline and cash-conversion cycle. 

    Working Capital Financing vs. Invoice Financing 

    For project-based businesses, it is also useful to distinguish between working capital financing and invoice financing. 

    Working Capital Financing 

    Working capital financing can be used to support broader operational requirements, including: 

    • Supplier payments 
    • Procurement 
    • Salaries 
    • Logistics 
    • Project execution 
    • Short-term business expenses 

    It can therefore be relevant when the business needs liquidity before or during project execution. 

    Invoice Financing 

    Invoice financing focuses on receivables. Once a business has completed the relevant work and raised an eligible invoice, financing against that receivable may provide access to liquidity before the customer completes its payment cycle, subject to the financing provider’s assessment and terms. 

    The two solutions therefore address different points in the cash-flow cycle. For a technology business, working capital may be particularly important during procurement, while invoice financing can potentially become relevant once eligible receivables have been generated. 

    Why This Matters for UAE Technology SMEs 

    The case reflects a wider challenge across UAE project-based businesses. Technology companies can have strong customers, established suppliers and healthy revenues but still experience pressure because their cash is tied up between: 

    Buying → Delivering → Invoicing → Collecting 

    This can become more pronounced when: 

    • Customer payment terms extend to 60 days 
    • Suppliers require upfront payments 
    • Multiple projects overlap 
    • Equipment has to be imported 
    • Freight costs increase 
    • Project sizes become larger 

    A business may therefore need more working capital precisely because it is growing. 

    What Businesses Can Learn From This Case 

    1. Revenue Growth Needs to Be Supported by Liquidity 

    Higher sales do not automatically mean higher available cash. Businesses should assess how much capital is required to fulfil those additional sales. 

    2. Map Your Cash Conversion Cycle 

    Understanding when money enters and leaves the business can reveal exactly where the funding gap occurs. 

    3. Consider Supplier Terms Carefully 

    Two projects with the same revenue can have very different funding requirements if their supplier payment terms differ. 

    4. Project-Based Inventory Still Uses Capital 

    Even when inventory is purchased specifically for a confirmed project, that equipment represents cash that cannot be used elsewhere until the project progresses. 

    5. Financing Should Grow With the Business 

    As project values and volumes increase, financing requirements may need to be reassessed rather than relying on an old facility size. 

    What Fincobox Brought to the Conversation 

    For this IT infrastructure business, the financing discussion was ultimately about more than obtaining a specific amount of money. It was about understanding how the business generated revenue, when it needed to spend, when customers paid and where additional liquidity could support growth. Fincobox evaluated the company’s project-driven model, customer payment cycle, supplier commitments, procurement requirements and existing financing arrangements to understand its additional working-capital needs.The business was seeking approximately AED 700,000–1 million, while also remaining open to starting with a smaller facility and scaling it as the financing relationship developed. Pasted text. This approach allows financing discussions to be connected to the actual needs of the business rather than simply focusing on a headline funding amount. 

    Preparing for Working Capital Financing in the UAE 

    Businesses considering financing can make the assessment process more efficient by preparing clear documentation around their operations. 

    For a project-based technology company, this can include: 

    Bank statements 

    To demonstrate actual cash-flow activity. 

    Purchase orders 

    To establish confirmed customer requirements. 

    Invoices 

    To demonstrate receivables and completed project milestones. 

    Supplier information 

    To understand procurement commitments and payment terms. 

    Project pipeline 

    To distinguish confirmed projects from potential opportunities. 

    Financial information 

    Including revenue, margins, expenses and existing obligations. 

    In this case, the business used Zoho for proposals, purchase orders and invoicing, and management indicated that relevant project documentation could be provided for underwriting review. Pasted text 

    The Bigger Lesson: Growth Needs Cash-Flow Planning 

    A business does not necessarily need financing because it is struggling. Sometimes, it needs financing because the business is growing faster than its cash cycle can support. 

    For a project-based IT infrastructure company, taking on more projects can mean: 

    • More equipment to procure 
    • More supplier payments 
    • More logistics costs 
    • More installation work 
    • More money tied up in projects 
    • More receivables waiting to be collected 

    If these factors are not planned for, growth itself can create financial pressure. That is why working capital should be treated as part of the growth strategy—not simply as an emergency source of cash. 

    How Fincobox Helps UAE SMEs Manage Growth 

    At Fincobox, we work with eligible UAE businesses to understand their financing requirements and explore suitable funding solutions. Depending on the business profile and credit assessment, solutions can include invoice discounting, revenue-based financing and other working-capital structures. 

    For project-based businesses, the starting point is understanding the cash-flow cycle. 

    When does the business pay suppliers? 

    When does it procure inventory? 

    When does it complete projects? 

    When does it invoice customers? 

    And when does the cash actually arrive? 

    Once those questions are understood, businesses can make more informed decisions about the type and amount of financing they may require. 

    Conclusion 

    This case of a Dubai-based IT infrastructure business demonstrates a common challenge faced by growing UAE SMEs: the need to fund today’s project costs while waiting for tomorrow’s customer collections. With annual revenue historically in the AED 7–8 million range, growing project activity and an additional working-capital requirement of approximately AED 700,000–1 million, the business needed greater liquidity to manage procurement and supplier payments across multiple projects. Pasted text 

    Fincobox approached the requirement by looking at the complete business cycle from customer orders and procurement to project execution and collections. If your business has confirmed projects, rising procurement requirements or cash tied up in customer receivables, Fincobox can help you explore financing options designed around your business needs. 

    Explore your financing options with Fincobox today. 
  • 5 Cash Flow Mistakes UAE SMEs Should Avoid This Black Friday

    5 Cash Flow Mistakes UAE SMEs Should Avoid This Black Friday

    Black Friday can bring a significant sales opportunity for UAE small and medium-sized enterprises (SMEs). From e-commerce brands selling through Amazon and Noon to wholesalers supplying retailers across Dubai, Abu Dhabi and other emirates, businesses often prepare for the season by increasing inventory, launching promotions and investing in advertising. However, higher sales can also create a temporary cash shortage. Businesses may need to pay suppliers, cover delivery costs and increase marketing expenditure before receiving payments from customers or online marketplaces. Even when orders are growing, the money required to fulfil them may not be immediately available. This is why Black Friday cash flow management matters just as much as sales planning. Businesses need to understand how much cash they will require, when payments are due and whether their available working capital can support the expected increase in demand. 

    Here are five cash flow mistakes UAE SMEs should avoid before Black Friday, along with practical ways to prevent them. 

    1. Assuming Higher Sales Automatically Mean More Cash 

    A rise in sales does not necessarily mean more cash is available in the business account. 

    Consider a UAE e-commerce SME expecting AED 500,000 in Black Friday sales. To achieve that target, the business may need to purchase inventory in advance, increase advertising spend, hire temporary staff and cover additional packaging and delivery costs. Meanwhile, some payments may remain tied up in marketplace settlement cycles or outstanding B2B invoices. For example, a seller operating through Amazon UAE or Noon may record sales before the corresponding settlement reaches its bank account. If supplier payments are due during this period, the business could experience a cash shortage despite strong sales. The solution is to forecast cash inflows and outflows alongside revenue. 

    Before launching promotions, estimate: 

    • Expected sales and the timing of customer payments. 
    • Inventory and supplier payments required before the campaign. 
    • Advertising, delivery, packaging and staffing costs. 
    • Discounts and their impact on gross margins. 
    • Cash available for rent, salaries and other regular expenses. 

    Practical tip: Prepare a weekly cash flow forecast covering the weeks before Black Friday, the campaign period and the following month. This will help identify funding gaps before they affect operations. 

    2. Overstocking Without Calculating Working Capital Requirements 

    Having enough inventory is essential during Black Friday. However, purchasing too much stock can leave an SME with insufficient cash for other expenses. For UAE retailers and e-commerce businesses, the challenge is balancing product availability with the cost of holding inventory. Imported products may also require advance supplier payments, shipping charges, customs-related costs and other expenses before the goods are ready to sell. Suppose a retailer invests AED 150,000 in additional inventory but sells only 60% of it during the promotional period. The remaining stock continues to tie up capital that could have been used to pay suppliers, fund marketing or support regular operations. 

    Instead of ordering stock based solely on last year’s sales or an optimistic forecast, consider these questions: 

    • Which products sold fastest during previous promotional periods? 
    • How much inventory is already available? 
    • What is the minimum stock required to meet expected demand? 
    • When must suppliers be paid? 
    • How much cash will remain if sales fall below expectations? 

    A three-scenario forecast can help businesses prepare for different outcomes: 

    Scenario Planning approach 
    Best case Strong demand and faster inventory turnover 
    Expected case Sales based on realistic historical performance 
    Worst case Lower sales, slower collections and unsold inventory 

    Practical tip: Prioritise products with proven demand and calculate the cash required to replenish them. Working capital for Black Friday should cover realistic inventory needs without putting essential operating expenses at risk. 

    3. Ignoring the Gap Between Supplier Payments and Customer Collections 

    One of the most common cash flow problems for UAE SMEs is the difference between when money must be paid out and when it is received. A business may have confirmed sales but still need to wait for marketplace settlements or customers paying on 30-, 60- or 90-day credit terms. Suppliers, however, may require deposits or payment before dispatch.  The business records AED 150,000 in sales, but it must fund the AED 100,000 inventory purchase before receiving the corresponding cash. It may also have to pay for advertising, delivery and other operating costs during the waiting period. This is a working capital gap. For UAE SMEs, managing this gap requires a clear view of supplier payment terms, customer credit periods and marketplace settlement schedules. 

    Practical tip: Map expected receipts against payment due dates. If the business regularly pays suppliers before collecting customer payments, consider whether additional working capital is needed to bridge the gap. 

    4. Increasing Marketing Spend Without Measuring Its Cash Impact 

    Black Friday advertising can become expensive as businesses compete for attention across Google, social media, marketplaces and influencer campaigns. Increasing the advertising budget may generate more orders, but it can also drain cash quickly if campaigns produce low-margin sales or take longer than expected to become profitable. For example, a UAE online retailer might spend AED 25,000 on a promotional campaign to generate AED 100,000 in sales. That does not automatically mean the campaign has delivered a strong financial return. Product costs, delivery, marketplace fees, discounts and other expenses still need to be deducted. 

    Before increasing marketing spend, monitor: 

    • Customer acquisition cost: How much does it cost to acquire a customer? 
    • Return on ad spend: How much revenue does each advertising dirham generate? 
    • Gross margin: How much remains after the cost of products sold? 
    • Conversion rate: How effectively does traffic turn into orders? 
    • Cash collection time: When will the revenue become available to spend? 

    Also, avoid assuming that all sales revenue can immediately be reinvested in advertising. 

    Practical tip: Set a campaign budget based on expected margins and available cash, not just competitors’ spending or ambitious sales targets. Review campaign performance regularly and redirect spending away from campaigns that fail to meet your targets. 

    5. Waiting Until Cash Runs Low to Explore Financing 

    Many businesses begin exploring financing only when they are struggling to pay suppliers or fulfil new orders. By then, a funding requirement that could have been planned in advance may become urgent. For UAE SMEs preparing for Black Friday, the better approach is to calculate the potential cash gap before the season and evaluate financing options early. The appropriate option depends on why the business needs capital, how it generates revenue and when it expects to repay the funding. 

    Which financing option could help? 

    Financing option When it may be appropriate 
    Invoice financing or invoice discounting When cash is tied up in eligible unpaid invoices and the business needs liquidity before customers pay. 
    Revenue-based financing When a business has established revenue and needs capital for inventory, marketing or expansion, subject to the facility’s terms. 
    Working capital financing When the business needs funding for short-term operating expenses or a temporary cash flow gap. 
    Purchase order financing When a business needs help covering supplier costs to fulfil an eligible confirmed order. 

    These options serve different purposes and are not interchangeable. Businesses should compare the fees, repayment structure, eligibility criteria and total financing cost before choosing a solution. 

    For example, Fincobox offers liquidity solutions for eligible UAE SMEs, including invoice discounting, Revenue-Based Liquidity, short-term working capital and purchase order liquidity. Its invoice discounting solution allows eligible businesses to access a portion of their invoice value before the buyer pays, subject to assessment and applicable terms. Businesses can explore Fincobox’s liquidity solutions to understand which options may fit their requirements. For more detail, read Fincobox’s guides to invoice discounting for small businesses and getting started with Revenue-Based Financing. 

    Practical tip: Start by calculating the amount and duration of the expected cash shortfall. Financing should address a defined business requirement, not compensate for consistently weak margins or uncontrolled spending. 

    Black Friday Cash Flow Checklist for UAE SMEs 

    Use this checklist before launching your promotions to identify potential risks and prepare your finances. 

    • Forecast sales: Use realistic estimates based on previous performance and current demand. 
    • Calculate inventory costs: Identify how much stock you need and when suppliers must be paid. 
    • Map payment cycles: Check when marketplace settlements and customer invoices are expected to clear. 
    • Review supplier terms: Explore whether payment dates or deposits can be negotiated. 
    • Set a cash buffer: Keep enough liquidity for salaries, rent, logistics and other essential expenses. 
    • Monitor marketing returns: Track campaign performance against margins and cash requirements. 
    • Prepare alternative scenarios: Model what happens if sales are lower or payments arrive later than expected. 
    • Identify funding gaps early: Evaluate suitable UAE SME financing options before liquidity becomes urgent. 

    Conclusion: Plan Your Cash Flow Before Black Friday Sales Begin 

    Black Friday can help UAE SMEs increase sales, attract new customers and move inventory. But the opportunity comes with additional costs and tighter payment timelines. The key is to prepare for the financial demands of the season before launching promotions. Businesses that forecast inventory purchases, track marketplace settlements, control advertising expenditure and plan supplier payments are better positioned to manage seasonal demand. If the forecast identifies a temporary funding gap, explore suitable working capital solutions early. Compare the costs and repayment terms, and choose an option that fits the business’s cash flow and repayment capacity. 

    Preparing for Black Friday is not just about having enough stock to sell. It is about having enough cash to deliver every order and keep the business running after the sale ends. If your business is preparing for the upcoming sales season, explore Fincobox’s financing solutions for UAE SMEs to learn more about the options available to eligible businesses. 

    Frequently Asked Questions 

    1. What is Black Friday cash flow management? 

    Black Friday cash flow management involves planning the money entering and leaving a business during the promotional period. It includes forecasting sales receipts, inventory purchases, supplier payments, marketing costs and other expenses to ensure sufficient liquidity throughout the campaign. 

    2. How can UAE SMEs prepare their working capital for Black Friday? 

    UAE SMEs should forecast expected sales, calculate inventory requirements, review supplier payment terms and map customer and marketplace settlement schedules. They should also maintain a cash buffer and identify potential funding gaps before increasing inventory or advertising expenditure. 

    3. Why can a business experience cash flow problems despite high Black Friday sales? 

    A business may record strong sales but wait days or weeks for marketplace settlements or customer payments. Meanwhile, supplier invoices, salaries, delivery charges and advertising bills may already be due. This timing mismatch can create a temporary cash shortage even when sales are growing. 

    4. What financing options are available to UAE SMEs for Black Friday? 

    Depending on their circumstances, eligible UAE SMEs may consider invoice financing, invoice discounting, revenue-based financing, short-term working capital facilities or purchase order financing. The appropriate option depends on the business’s funding requirement, revenue profile, receivables and repayment capacity. 

    5. Can a UAE SME qualify for financing before Black Friday? 

    Potentially, yes. Eligibility depends on the financing provider’s assessment, the business’s registration and operating history, revenue, financial information and the type of facility requested. Businesses should review the applicable criteria and prepare the required documents in advance. Approval is not guaranteed. 

    6. How early should SMEs arrange financing for Black Friday? 

    Ideally, businesses should begin assessing their cash flow and funding requirements several weeks before their planned inventory purchases and marketing campaigns. This gives them time to review documentation, compare financing terms and address potential shortfalls before suppliers need payment. The actual lead time depends on the provider and facility. 

    7. Is revenue-based financing suitable for Black Friday inventory purchases? 

    It may be suitable for businesses with established revenue that need capital to fund inventory or marketing ahead of a sales period. However, businesses should assess the repayment structure, total cost and expected post-campaign revenue before proceeding. 

    8. How can Fincobox help eligible UAE SMEs manage Black Friday cash flow? 

    Fincobox offers liquidity solutions including invoice discounting, Revenue-Based Liquidity, short-term working capital and purchase order liquidity. Depending on the business’s circumstances and eligibility, these options may help address funding gaps associated with unpaid invoices, inventory purchases or order fulfilment. Businesses should review the applicable terms before applying. 

  • Working Capital Financing UAE: How an Abu Dhabi AV Business Managed Growth

    Working Capital Financing UAE: How an Abu Dhabi AV Business Managed Growth

    Winning a large project is usually a sign that a business is moving in the right direction. But for project-based companies, a larger order book can also create an immediate financing requirement. Before a project generates its full revenue, a business may need to purchase equipment, pay suppliers, hire technical staff and cover operating expenses. When customers pay according to project milestones, cash may not arrive at the same time as these expenses. This is where working capital financing in the UAE can become relevant. For businesses in audio-visual (AV) integration, technology installation, engineering, construction and other project-led sectors, the challenge is often not a lack of sales. It is the timing difference between when money needs to be spent and when customer payments are received. The case of an Abu Dhabi-based AV integration business illustrates this clearly. 

    Case Study at a Glance 

    Business Metric Case Study 
    Industry Audio-visual equipment installation & integration 
    Location Abu Dhabi, UAE 
    Invoiced revenue Approximately AED 500,000 
    Stated project pipeline Approximately AED 6.8 million 
    Estimated working-capital requirement Approximately AED 600,000 
    Typical project size AED 300,000+ 
    Supplier credit terms Approximately 30–60 days from some suppliers 
    Key requirement Team expansion, project execution and operating working capital 

    The business had restarted operations in 2024 and was entering a significant growth phase. Its pipeline included opportunities across government-related services, aviation and banking, with individual projects ranging from approximately AED 1 million to several million dirhams. The opportunity was there. The financing challenge was having sufficient liquidity to convert that pipeline into completed projects. 

    Why Project-Based Businesses Need Working Capital Financing in the UAE 

    Working capital is the money a business needs to keep its operations moving while it waits for revenue to turn into collected cash. For a project-based company, the cycle can look like this: Customer confirms project → Equipment is procured → Installation begins → Milestones are completed → Invoice is raised → Customer payment is received. The business spends money during several of the earlier stages, while significant cash inflows may only arrive later. That creates a working-capital gap. 

    For example, an AV integrator may have a confirmed customer order but still need to: 

    • Purchase equipment and technology 
    • Pay suppliers 
    • Hire or allocate project staff 
    • Fund installation and integration 
    • Cover salaries and operating expenses 
    • Wait for milestone payments 
    • Complete testing and commissioning before final collection 

    This is why revenue growth does not always mean stronger cash flow. A company can have a healthy sales pipeline and commercially viable projects while still experiencing short-term liquidity pressure. 

    The Abu Dhabi AV Business: From Pipeline to Execution 

    The business featured in this case operates in the audio-visual equipment installation and integration industry. 

    Its projects include: 

    • Control rooms 
    • Boardrooms 
    • Meeting rooms 
    • Government facilities 
    • Corporate environments 
    • Complex AV installations 

    The company primarily serves B2B and government-related customers and generally focuses on projects above AED 300,000. Unlike a traditional distributor that maintains significant inventory, the business largely follows an order-backed procurement model. Once a customer order is confirmed, equipment is sourced through established suppliers and deployed for that specific project. This approach can reduce unnecessary inventory. However, it also creates a financing requirement at a critical point: when a confirmed sale needs to be converted into actual project execution. 

    The Financing Challenge: AED 500K Revenue vs. AED 6.8M Pipeline 

    At the time of discussions with Fincobox, the business had approximately AED 500,000 in invoiced revenue and a stated project pipeline of around AED 6.8 million. On paper, the pipeline represented a significant growth opportunity. But a pipeline is not the same as collected cash. A project worth several million dirhams may require the company to commit funds well before the complete project value is received. Procurement, salaries, technical resources and other operating costs can all arise before final collection. The business therefore identified an estimated AED 600,000 working-capital requirement. The requirement was not simply about covering a temporary cash shortage. It was connected to the company’s ability to build the capacity required to execute its growth pipeline. 

    Understanding the Cash Conversion Cycle 

    One of the most useful ways to assess a business’s working-capital requirement is to understand its cash conversion cycle. For this AV integration business, the cycle can be simplified into five stages: 

    1. Procurement 

    The company purchases AV equipment and related technology required for the project. 

    2. Project Execution 

    Equipment is delivered, installed and integrated at the customer’s site. 

    3. Milestone Billing 

    The customer is invoiced according to agreed project milestones. 

    4. Testing and Commissioning 

    The project reaches its final stages, including testing, commissioning and submission of supporting documentation. 

    5. Collection 

    The customer makes the outstanding payment according to the agreed payment terms. The longer money remains tied up between procurement and collection, the greater the potential working-capital requirement. 

    Supplier and Customer Payment Terms Matter 

    Payment terms can significantly influence how much working capital a project requires. In this case, some suppliers offered approximately 30–60 days of credit, while others required significant upfront payment. 

    Customer payments could also be structured around project milestones, for example: 

    • 20% advance 
    • 35% after the first equipment delivery 
    • 35% after the second equipment delivery 
    • 20% after testing and commissioning 

    This structure gives the business access to cash at different stages. However, it does not necessarily eliminate the need for upfront liquidity. When multiple projects are running simultaneously, the timing differences between supplier payments, project expenses and customer collections can compound. This is one reason working capital financing in the UAE can be particularly relevant to project-based SMEs. 

    How Fincobox Assessed the Working-Capital Requirement 

    Rather than looking only at the amount requested, Fincobox assessed the business’s wider financial cycle. The assessment considered factors including: 

    • Nature of the business 
    • Customer profile 
    • Existing projects 
    • Future project pipeline 
    • Supplier payment terms 
    • Customer payment terms 
    • Invoicing structure 
    • Banking activity 
    • Project margins 
    • Existing financial obligations 

    This distinction matters. 

    A business looking for funding to procure equipment before a confirmed project may have a different financing requirement from a company that has already completed projects but is waiting for customers to pay outstanding invoices. The right financing structure depends on why the business needs capital, when it needs it and how the cash is expected to return to the business. 

    How Working Capital Financing Supported the Business’s Growth Plans 

    The business estimated its immediate working-capital requirement at approximately AED 600,000. A significant portion of this requirement related to scaling the team and supporting project execution. 

    Planned uses included: 

    • Hiring an additional Project Manager 
    • Hiring a Junior Solutions Architect 
    • Employee salaries 
    • Operational expenses 
    • Project-related working capital 

    This highlights an important point that is sometimes overlooked when discussing business financing: 

    People are also working capital. 

    A company winning larger contracts may need to hire project managers, engineers, architects or other specialists before the associated project revenue has been fully collected. 

    For a growing SME, having the right people available can be just as important as having equipment available. 

    Working Capital Financing vs. Invoice Financing 

    Working capital financing and invoice financing can both help address cash-flow gaps, but they solve different problems. 

    Factor Working Capital Financing Invoice Financing / Discounting 
    Primary purpose Fund broader operating and project-related requirements Unlock cash tied up in unpaid invoices 
    Best suited for Businesses needing liquidity for operations, people and project execution Businesses with eligible outstanding receivables 
    Funding trigger Overall business and working-capital requirement Eligible customer invoice 
    Typical use Salaries, procurement, operating costs and project execution Supplier payments, payroll, inventory and other short-term expenses 
    Cash-flow problem addressed Funding required before revenue is collected Delay between invoicing and customer payment 
    Key assessment factors Business model, cash flow, projects, obligations and funding requirement Invoice, customer, payment terms, documentation and business profile 

    For the Abu Dhabi AV business, both perspectives were relevant. 

    Working capital financing addressed the broader requirement around team expansion and project execution, while invoice financing could potentially provide liquidity against eligible project receivables. The important takeaway is that financing should be matched to the actual source of the cash-flow gap. 

    Where Invoice Financing Can Fit 

    Imagine an AV business completes an agreed project milestone and raises an invoice worth AED 500,000. The customer may have a payment period before the money reaches the company’s bank account. If the invoice is eligible for financing, the business may be able to access liquidity against the receivable before the customer settles the invoice, subject to assessment and applicable terms. 

    This can help reduce the effective waiting period between completing work and having usable cash available. Invoice financing can therefore be relevant for UAE SMEs that: 

    • Sell to customers on credit terms 
    • Have eligible outstanding invoices 
    • Experience 30-, 60- or 90-day payment cycles 
    • Need liquidity before customer collections 
    • Have established B2B or institutional customers 

    However, not every invoice will automatically qualify. The customer, invoice validity, payment terms, documentation and overall business profile can all influence eligibility. 

    What This Case Study Teaches UAE SMEs 

    1. A Strong Pipeline Can Increase the Need for Capital 

    A growing order book can require additional money for procurement, employees and execution before the associated revenue is collected. 

    2. Revenue and Cash Flow Are Not the Same 

    The business had approximately AED 500,000 in invoiced revenue alongside a stated pipeline of approximately AED 6.8 million. The difference illustrates why future sales opportunities cannot automatically be treated as available cash. 

    3. Payment Terms Should Be Part of Project Planning 

    Before accepting a large contract, businesses should map when they need to spend money and when they expect to receive customer payments. 

    4. Receivables Can Become a Liquidity Source 

    For eligible businesses, outstanding invoices may potentially be financed rather than waiting for the entire customer payment cycle. 

    5. Financing Should Start With the Cash-Flow Problem 

    Instead of asking only, “How much funding do we need?”, businesses should ask: 

    “When do we need the money, what will it fund, and when will the cash return to the business?” 

    That question can lead to a more practical financing strategy. 

    What Should a UAE SME Prepare Before Applying for Financing? 

    Businesses considering working capital financing in the UAE can make the assessment process more efficient by organising key financial and operational information in advance. Depending on the financing product and provider, this may include: 

    Recent Bank Statements 

    These can help demonstrate business cash-flow patterns and account activity. 

    Customer Information 

    Details about major customers and their payment behaviour can help establish the quality and timing of receivables. 

    Project Pipeline 

    Separate confirmed projects from potential opportunities. A confirmed purchase order or contract provides a different basis for assessment than an early-stage sales opportunity. 

    Outstanding Invoices 

    Include invoice dates, amounts, customers and payment terms where applicable. 

    Supplier Commitments 

    Highlight suppliers requiring upfront payments or other significant commitments. 

    Financial Information 

    Prepare revenue, margins, operating expenses and existing financial obligations. 

    Supporting Project Documents 

    Contracts, purchase orders, delivery notes and other relevant documents can help provide context around the financing requirement. 

    Choosing the Right Financing Structure 

    The most appropriate financing option depends on where the cash-flow pressure originates. If the business has unpaid eligible invoices, invoice discounting may be worth exploring. If the business has established revenue and needs capital to support growth, revenue-based liquidity may be relevant depending on eligibility. If the requirement is connected to day-to-day operating expenses and project execution, short-term working-capital facilities may be considered. And where a business has a confirmed purchase order but needs funds to fulfil it, purchase-order liquidity may be relevant. Fincobox offers liquidity solutions including invoice discounting, revenue-based liquidity, short-term working-capital arrangements and purchase-order liquidity for eligible UAE businesses. The key is to start with the cash-flow requirement rather than selecting a financing product first. 

    Conclusion: Turning Business Opportunities Into Executed Projects 

    The Abu Dhabi AV integration business demonstrates why working capital financing in the UAE can be an important consideration for growing project-based companies. With approximately AED 6.8 million in stated pipeline opportunities and an estimated AED 600,000 working-capital requirement, the business needed to look beyond revenue forecasts and understand the timing of its cash flows. Fincobox assessed the business model, project cycle, customer payment structure and funding requirements to explore financing options aligned with its growth plans. The broader lesson for UAE SMEs is straightforward: When growth is ahead of cash flow, the right financing structure can help bridge the gap between opportunity and execution. For businesses managing long payment cycles, project expenses or growing receivables, working capital financing and invoice financing can form part of a broader cash-flow strategy. 

    Looking to fund your next stage of growth? Explore financing options with Fincobox. 

    Frequently Asked Questions About Working Capital Financing UAE 

    1. What is working capital financing in the UAE? 

    Working capital financing is funding used to support a business’s short-term operating and cash-flow requirements. Depending on the business and facility, this can include expenses related to procurement, salaries, project execution and other operating needs. 

    2. Who can benefit from working capital financing? 

    It can be relevant to SMEs that experience a timing gap between business expenses and customer collections. Project-based businesses, B2B companies, distributors, contractors and other growing businesses may have working-capital requirements, subject to the financing provider’s eligibility criteria. 

    3. What is the difference between working capital financing and invoice financing? 

    Working capital financing addresses broader operating or project-related funding requirements. Invoice financing is specifically structured around eligible unpaid invoices, allowing a business to potentially access liquidity before its customer pays. 

    4. What documents are generally required for financing? 

    Requirements vary by provider and financing product. Businesses may be asked for company and owner KYC information, company registration documents, bank statements, operational data and supporting financial or invoice documentation. Fincobox states that businesses need basic owner KYC, company registration and business operational information during its application process. 

    5. Can a business use invoice discounting to improve working capital? 

    Potentially, yes. Eligible businesses can use invoice discounting to unlock part of the value of qualifying outstanding invoices before customer payment. Fincobox states that eligible businesses can access up to 90% of invoice value, subject to assessment and applicable terms. 

    6. How do I decide which financing option is right for my business? 

    Start by identifying the source and timing of the cash-flow gap. If cash is tied up in unpaid invoices, invoice discounting may be relevant. If the business needs broader operating liquidity, working-capital financing may be more appropriate. Businesses with established revenue or confirmed purchase orders may have other financing options to consider. 

    Author & Reviewer 

    Written by:  Anjali Chauhan, Creative Head, Fincobox 

    Reviewed by: Adithya  

  • What Happens When Your Cash Conversion Cycle Gets Longer?

    What Happens When Your Cash Conversion Cycle Gets Longer?

    Imagine your sales are growing, new customers are coming in and your order book looks stronger than ever. Yet, every month, you still find yourself asking: “Why do we have so much business but not enough cash?” For many growing businesses, the problem is not a lack of sales. It is timing. Customers may take longer to pay. Inventory may sit in the warehouse for longer. Suppliers may shorten their payment terms. Each change means more cash stays tied up inside the business. This is where the cash conversion cycle (CCC) becomes important. 

    What Is the Cash Conversion Cycle? 

    The cash conversion cycle measures how long it takes for the money a business puts into its operations to come back as collected cash. 

    The basic formula is: 

    Cash Conversion Cycle = Inventory Days + Receivable Days − Payable Days 

    In simple terms, it answers: 

    How long does my money stay tied up before it comes back into the business? 

    A simple UAE example 

    Consider a Dubai-based distributor: 

    • Inventory is held for 30 days 
    • Customers take 60 days to pay 
    • Suppliers give 30 days to pay 

    So: 

    30 + 60 − 30 = 60-day Cash Conversion Cycle 

    The business effectively has to fund around 60 days of its operating cycle. 

    Now imagine customers start taking 90 days to pay. 

    30 + 90 − 30 = 90 days 

    The business has just added 30 days to its cash requirement, even though its sales process has not changed. 

    What happens when each part changes? 

    Change Example Impact on CCC 
    Customers pay later Receivables: 60 → 90 days +30 days 
    Inventory sells slower Inventory: 30 → 45 days +15 days 
    Suppliers give less time Payables: 30 → 15 days +15 days 
    Suppliers give more time Payables: 30 → 45 days −15 days 

    This is why a business can suddenly need more working capital without actually becoming less profitable. 

    Why Does a Longer Cash Conversion Cycle Matter? 

    A longer CCC means more money is committed to day-to-day operations before it returns as cash. 

    For a UAE SME, that can affect the ability to: 

    • Pay suppliers on time 
    • Replenish inventory 
    • Fund payroll and operating expenses 
    • Spend on marketing 
    • Take on larger customer orders 
    • Invest in expansion 

    The impact becomes more noticeable as the business grows. For example, suppose a UAE B2B company invoices AED 1 million every month. If customers pay in 30 days, roughly one month’s sales may be sitting in receivables. If the average collection period moves to 90 days, the business could have substantially more cash tied up in outstanding invoices. The company may still be profitable. It simply has to wait longer to access the cash generated by its sales. 

    What Makes the Cash Conversion Cycle Longer? 

    There are three main areas to watch: receivables, inventory and payables. 

    1. Customers Are Taking Longer to Pay 

    This is one of the most common reasons a company’s CCC increases. A UAE wholesaler might have 30-day payment terms on paper, but some customers may actually pay in 45, 60 or even 90 days. For a business invoicing AED 500,000 a month, an additional 30 days in collections can leave a significant amount of additional capital sitting in receivables. Before looking for financing, check why payments are late. Common causes include: 

    • Invoice errors 
    • Customer approval delays 
    • Disputes 
    • Weak collection follow-up 
    • Informal extensions of credit 
    • Customers consistently paying beyond agreed terms 

    Improving collections can sometimes release cash without taking on additional financing. But when long payment cycles are a normal part of the business, receivables finance or invoice discounting UAE solutions may help bridge the gap. For eligible businesses, Fincobox’s Invoice Discounting is designed to unlock liquidity against outstanding invoices rather than requiring the business to wait until the full customer payment cycle is complete. 

    2. Inventory Is Taking Longer to Sell 

    Inventory is another common cash-flow drain. Consider a UAE e-commerce business preparing for Ramadan or another major sales period. It purchases AED 400,000 of inventory, expecting most of it to sell within 30 days. But demand is slower than expected, and after a month, only half the stock has moved. The remaining AED 200,000 is not necessarily a loss. But it is also not available to: 

    • Purchase faster-moving products 
    • Pay suppliers 
    • Fund marketing 
    • Cover operating expenses 

    The issue is therefore not simply how much inventory a business holds. It is how quickly that inventory turns back into cash. Before using financing to purchase more stock, businesses should look at inventory turnover, margins and actual demand. Where a business has established revenue and needs capital for inventory or growth, Fincobox’s Revenue-Based Liquidity may be relevant for eligible businesses. 

    3. Suppliers Want Payment Sooner 

    The third part of the CCC equation is often overlooked. 

    Imagine a UAE distributor whose: 

    • Customers pay in 60 days 
    • Suppliers give 45 days 

    The business already has a 15-day gap to manage. If the supplier changes the terms to 30 days, the gap becomes: 

    60 − 30 = 30 days 

    The customers have not changed. Sales have not changed.But the business now needs to fund an additional 15 days. This is why supplier negotiations can have a meaningful effect on business liquidity UAE. Depending on the transaction, businesses may also explore options such as payable financing, vendor finance or supply-chain finance. 

    Why Growth Can Increase Your Cash Requirement 

    One of the less obvious realities of business growth is that more sales can require more cash. Imagine a UAE company growing from AED 200,000 to AED 1 million in monthly sales. At AED 200,000 a month, customers paying within 30 days may leave a manageable amount in receivables. At AED 1 million a month, if customers take 60–90 days to pay, the amount tied up in receivables can increase significantly. And growth may also require: 

    • More inventory 
    • More employees 
    • More logistics 
    • More marketing 
    • Larger supplier payments 

    So the business may be generating more revenue while simultaneously needing more working capital UAE to support that revenue. This is why cash planning becomes increasingly important as an SME scales. 

    Profit Is Not the Same as Cash 

    A business can be profitable and still have a cash-flow problem. Consider a UAE company that makes a AED 200,000 sale in September, but the customer is not due to pay until November. The sale contributes to revenue and potentially profit, but the AED 200,000 is not yet available in the company’s bank account. Meanwhile, the business may have supplier invoices, payroll and operating expenses due today. That is the practical difference between profit and cash flow. Profit tells you what the business earned. Cash flow tells you when that money is actually available to use. For businesses with long payment cycles, that timing difference can create a genuine liquidity requirement even when underlying sales are healthy. 

    What Should You Do When Your Cash Conversion Cycle Gets Longer? 

    Before looking for business financing UAE, find out what has actually changed. 

    Start with receivables 

    Compare your contractual payment terms with your actual collection period. If customers are supposed to pay in 30 days but are actually paying in 55 days, investigate why. Improving collections may be the simplest way to release cash. 

    Review inventory 

    Look at: 

    • Which products are moving slowly? 
    • How long has stock been sitting? 
    • Are you purchasing based on actual demand? 
    • Are seasonal assumptions still accurate? 

    The goal is not necessarily to hold less inventory. It is to hold the right inventory at the right time. 

    Review supplier terms 

    If your business has a strong payment history, consider whether suppliers may offer longer payment terms. Moving from 30-day to 45-day terms, for example, can give the business additional time to collect customer payments before paying suppliers. 

    Then consider financing 

    If the longer cycle is a normal part of the business rather than a temporary problem, financing may help bridge the timing gap. The important part is matching the financing to the reason cash is tied up. 

    Where Different Fincobox Solutions Can Fit 

    Different cash-flow problems call for different financing structures. For eligible UAE businesses, Fincobox offers several non-dilutive liquidity solutions that correspond to different points in the cash conversion cycle. 

    Cash is tied up in unpaid invoices? 

    Invoice Discounting can help eligible businesses unlock liquidity against outstanding invoices instead of waiting for the entire customer payment cycle. 

    You have consistent revenue but need capital for growth or inventory? 

    Revenue-Based Liquidity is designed for businesses with established revenue that need funding for growth-related requirements. 

    You need short-term cash for operational requirements? 

    Short-Term Working Capital can help address temporary funding needs across the operating cycle. You have a confirmed customer order but need capital to fulfil it? 

    Purchase Order Liquidity is designed to help eligible businesses fund qualifying purchase orders before receiving customer payment. The point is not to choose financing first. It is to identify where the cash-flow gap is, then assess whether financing is an appropriate way to bridge it. Fincobox’s solutions are non-dilutive, meaning businesses do not exchange ownership for the financing. 

    5 Warning Signs Your Cash Conversion Cycle Needs Attention 

    You do not need to wait until cash becomes critically tight. 

    Watch for these signs: 

    1. Sales are rising, but available cash is not. 

    Revenue is growing, but the bank balance is not keeping pace. 

    2. Receivables are growing faster than revenue. 

    Customers are taking longer to pay or outstanding invoices are accumulating. 

    3. Inventory keeps building. 

    Stock is increasing without a corresponding increase in sales. 

    4. Supplier payment extensions are becoming routine. 

    Repeatedly asking suppliers for more time can point to a working capital gap. 

    5. You are turning down orders because you cannot fund them. 

    When lack of liquidity starts limiting your ability to accept profitable business, cash flow has become a growth constraint. 

    The Bottom Line 

    Your cash conversion cycle is more than an accounting formula. 

    It tells you how long your money is tied up before it returns to the business. When customers pay later, inventory moves more slowly or suppliers require payment sooner, the cycle gets longer and your working capital requirement can increase. The first response does not always need to be financing. Start by improving collections, reviewing inventory and negotiating supplier terms. But if a longer cash cycle is a normal part of how your business operates, the right cash flow solutions UAE can help you manage the gap without allowing working capital constraints to slow down growth. For eligible UAE SMEs, options such as invoice discounting, revenue-based liquidity, short-term working capital and purchase-order liquidity can address different cash-flow requirements. Because ultimately, a growing business needs more than sales. It needs enough liquidity to keep operating while it waits for those sales to turn back into cash. Revenue tells you how much you sold. Your cash conversion cycle tells you how long you have to wait to use that money. 

    Frequently Asked Questions 

    What is a cash conversion cycle? 

    The cash conversion cycle measures how long it takes for a business to convert money invested in inventory and operations back into collected cash from customers. 

    What causes the cash conversion cycle to increase? 

    The CCC can increase when customers take longer to pay, inventory takes longer to sell, or suppliers require payment sooner. 

    Is a longer cash conversion cycle bad for an SME? 

    Not necessarily. Some industries naturally operate with longer cash cycles. The key question is whether the business has enough working capital and liquidity to support that cycle. 

    How can a business shorten its cash conversion cycle? 

    Businesses can improve collections, reduce unnecessary inventory, improve inventory turnover and negotiate suitable supplier payment terms. 

    Can invoice discounting help with cash flow? 

    For eligible businesses with qualifying outstanding invoices, invoice discounting can provide access to part of the invoice value before the customer makes the payment, subject to the provider’s assessment and terms. 

    What is revenue-based financing? 

    Revenue-based financing is a form of business financing where repayment is structured around a company’s revenue or sales performance rather than exchanging equity for capital. The exact structure varies by provider. 

    What is purchase order financing? 

    Purchase order financing provides capital to help eligible businesses fulfil confirmed purchase orders, particularly when they need to pay suppliers or purchase materials before receiving payment from the customer. 

    Does Fincobox provide working capital solutions in the UAE? 

    Yes. Fincobox currently offers Invoice Discounting, Revenue-Based Liquidity, Short-Term Working Capital and Purchase Order Liquidity for eligible UAE businesses. 

    Can a business be profitable but still have cash-flow problems? 

    Yes. A business may record revenue and profit from sales while the corresponding cash remains tied up in unpaid invoices or inventory. This is why cash-flow management remains important even when sales and profitability are healthy. 

  • Need Business Capital Without Giving Up Equity? What Are Your Options?

    Need Business Capital Without Giving Up Equity? What Are Your Options?

    A UAE business may have a large order but need to pay its supplier first. An e-commerce brand may need inventory ahead of Ramadan or a seasonal sales peak. A B2B company may have AED 500,000 in outstanding invoices but still be waiting 60 or 90 days to get paid. The business may be profitable. The problem is timing. For founders who want to raise capital without giving away ownership, non-dilutive funding UAE options can provide an alternative to equity financing. Depending on the business model and cash-flow requirement, this can include revenue-based financing, invoice discounting, purchase order liquidity and short-term working capital. 

    The key is choosing financing based on where the cash-flow gap actually exists. 

    What Is Non-Dilutive Funding? 

    Non-dilutive funding allows a business to access capital without selling ownership in the company. Unlike equity financing, founders do not give an investor a percentage of the business in exchange for funding. However, non-dilutive financing is not free capital. The business still has an agreed financial obligation, whether repayment is linked to revenue, an invoice, a purchase order or a defined financing arrangement. 

    Common forms include: 

    • Revenue-based financing 
    • Invoice discounting 
    • Purchase order financing 
    • Short-term working capital 
    • Trade and supply-chain finance 
    • Inventory financing 

    The right option depends on why the business needs the money and when the business expects to receive cash. 

    Start With the Cash-Flow Problem, Not the Financing Product 

    Consider a Dubai-based distributor that receives a AED 500,000 order from a corporate customer. The customer will pay 60 days after delivery, but the supplier wants payment upfront. The distributor does not necessarily have a sales problem. It has a working capital problem. This distinction matters. 

    The same applies to: 

    • A D2C brand preparing inventory for a seasonal campaign 
    • A SaaS company investing in customer acquisition 
    • A wholesaler waiting for B2B customers to pay 
    • A manufacturer that needs supplier funding to fulfil a confirmed order 
    • An online seller waiting for marketplace settlements 

    Each situation can require a different financing structure. 

    5 Business Financing Options for UAE SMEs 

    1. You Have Consistent Revenue but Need Capital to Grow 

    Consider: Revenue-Based Financing 

    Revenue-based financing can be relevant for businesses with established and relatively consistent sales that want capital for growth without giving up equity. For example, a UAE e-commerce brand generating regular monthly sales may want additional capital to increase inventory or marketing spend before revenue from those activities comes in. 

    Fincobox’s Revenue-Based Liquidity is positioned for businesses with consistent online sales and can be used for areas such as inventory, marketing and product expansion. Fincobox states that eligible businesses may access capital of up to 2.5–3 times monthly revenue, subject to credit assessment and applicable terms. This can make revenue-based financing relevant when the business has proven sales but does not want to raise equity for its next growth opportunity. 

    2. Your Cash Is Stuck in Unpaid Invoices 

    Consider: Invoice Discounting 

    For many UAE B2B businesses, the gap between issuing an invoice and receiving payment can put pressure on working capital. Imagine a wholesaler invoices a customer AED 200,000 with payment due in 60 days. Meanwhile, the wholesaler still needs to pay suppliers, salaries, logistics costs and other operating expenses. Invoice discounting can allow an eligible business to access part of the invoice value before the customer pays. Fincobox currently states that eligible businesses can access up to 90% of invoice value, subject to assessment and applicable terms. Its FAQ also notes that the facility is completed when the buyer honours the invoice, which is typically within a 2–3-month payment cycle. This can be particularly relevant for UAE wholesalers, manufacturers, B2B service providers and other businesses that regularly operate on credit terms. 

    3. You Have a Large Order but Need Cash to Fulfil It 

    Consider: Purchase Order Liquidity 

    Sometimes the financing requirement appears before an invoice. For example, a UAE trading company receives a confirmed AED 750,000 customer order but needs AED 400,000 to purchase the goods from its supplier. Waiting until the order is fulfilled may not be practical. Purchase order liquidity is designed around this type of situation, helping eligible businesses access capital to fulfil qualifying orders. It may be relevant when a business: 

    • Has a confirmed customer order 
    • Needs upfront supplier payments 
    • Has insufficient working capital to fulfil the order 
    • Expects customer payment after delivery 

    The important consideration is whether the order has sufficient margin and predictable payment terms to support the financing cost. 

    4. You Need Cash for Day-to-Day Operations 

    Consider: Short-Term Working Capital 

    Not every funding requirement comes from an invoice or purchase order. A UAE SME may need additional liquidity to cover: 

    • Supplier payments 
    • Inventory purchases 
    • Payroll 
    • Marketing 
    • Logistics 
    • Rent and operating expenses 
    • Seasonal demand 

    Short-term working capital can help bridge these temporary gaps. Fincobox currently lists Short-Term Forfaiting Arrangements among its liquidity solutions for businesses looking to manage day-to-day cash flow and working capital requirements. The important point is to match the financing period with the underlying cash-flow need. Short-term funding should not be used to mask a long-term structural cash-flow problem. 

    5. You Need to Stock Up Before Sales Come In 

    Consider: Inventory Financing or Revenue-Based Liquidity 

    Inventory can absorb significant amounts of cash before it generates revenue. For example, a UAE e-commerce brand may know that demand will increase during Ramadan, Eid or a major shopping campaign. Waiting for existing inventory to sell before placing the next order could mean missing the sales opportunity. Financing can help the business purchase stock while preserving cash for other operating expenses. For businesses with established online sales, revenue-based liquidity may be relevant. Fincobox specifically positions its Revenue-Based Liquidity for inventory, marketing and product expansion needs. Before taking financing for inventory, businesses should still consider stock turnover, margins, expected demand and the time required to convert inventory back into cash. 

    Which Financing Option Fits Your Situation? 

    Your business problem Financing option to explore 
    Cash tied up in unpaid invoices Invoice Discounting 
    Consistent revenue + growth opportunity Revenue-Based Liquidity 
    Confirmed order + supplier payment needed Purchase Order Liquidity 
    Short-term operating cash gap Working Capital 
    Inventory needed before expected sales Revenue-Based Liquidity / Inventory Financing 

    The goal is not to find the financing product with the biggest headline amount. It is to find the structure that matches your cash-conversion cycle, revenue model and repayment capacity. 

    Revenue-Based Financing vs. Invoice Discounting 

    These two options are often mentioned together, but they address different cash-flow situations. 

     Revenue-Based Financing Invoice Discounting 
    Based on Business revenue Eligible unpaid invoices 
    Best for Growth and expansion Bridging payment cycles 
    Typical use Inventory, marketing, product expansion Working capital 
    Repayment Linked to agreed revenue/sales structure Connected to invoice settlement 
    Equity dilution No No 

    For example, a UAE D2C brand with consistent online sales may consider Revenue-Based Liquidity for inventory or marketing. A B2B wholesaler waiting 60 days for an AED 200,000 invoice to be paid may instead consider invoice discounting. The financing need determines the product. 

    What About SME Loans in the UAE? 

    Traditional SME loans UAE remain one option for businesses seeking capital. However, businesses should compare the complete financing structure rather than focusing only on the amount available. 

    Consider: 

    • Total financing cost 
    • Repayment frequency 
    • Collateral requirements 
    • Personal guarantees 
    • Processing time 
    • Documentation 
    • Minimum operating history 
    • Revenue requirements 
    • Effect on monthly cash flow 

    The UAE Central Bank’s SME Customer Protection Regulation C 2/2026 came into effect on 13 September 2026. Among other requirements, its responsible-financing provisions state that licensed financial institutions should not provide credit beyond amounts a customer is capable of servicing, based on an assessment of the customer’s ability to meet credit obligations. For businesses, the principle is straightforward: the amount of financing should make sense alongside the company’s ability to repay it. 

    How Fincobox Supports UAE SMEs 

    Fincobox provides digital-first, non-dilutive liquidity solutions for eligible UAE SMEs. 

    Its current product range includes: 

    • Revenue-Based Liquidity – funding linked to business revenue 
    • Invoice Discounting – liquidity against eligible outstanding invoices 
    • Short-Term Forfaiting Arrangements – designed for short-term working capital requirements 
    • Purchase Order Liquidity – funding to help fulfil eligible customer orders 

    Fincobox currently advertises financing from AED 50,000 to AED 2 million, with final limits subject to credit evaluation. For Revenue-Based Liquidity, Fincobox states that eligible businesses may access up to 2.5–3 times monthly revenue, while its FAQ says MSMEs, D2C and e-commerce businesses with 6+ months of operating history and AED 100,000+ monthly revenue typically qualify, subject to assessment. These figures are not guaranteed funding amounts. Eligibility, limits and terms depend on the individual business assessment. 

    Before You Apply, Ask These 4 Questions 

    Before taking any form of business financing, look at: 

    1. Where exactly is cash getting stuck? 

    Receivables, inventory, supplier payments or operating expenses? 

    2. When will the business generate the cash to settle the facility? 

    Be specific about the expected payment or sales cycle. 

    3. What will the financing cost? 

    Look beyond the headline funding amount and understand the total obligation. 

    4. Can the business comfortably meet that obligation? 

    Financing should support the business’s cash flow, not create another cash-flow problem. 

    Final Thoughts 

    You do not necessarily need to give up equity every time your business needs capital. For UAE SMEs, non-dilutive funding options can address different points in the cash-flow cycle  from unpaid invoices and confirmed purchase orders to inventory requirements and growth investment. If your business has consistent revenue, Revenue-Based Liquidity may be worth exploring. If cash is tied up in eligible invoices, Invoice Discounting may be more relevant. If you have a confirmed order waiting to be fulfilled, Purchase Order Liquidity may fit the requirement. For UAE businesses looking for capital without giving up ownership, understanding the difference between these options is the first step towards making a more informed financing decision. 

    Explore Fincobox’s liquidity solutions to identify the option that fits your business cash-flow needs. 

    Frequently Asked Questions 

    1. Can I get business financing in the UAE without giving up equity? 

    Yes. UAE businesses can explore non-dilutive options such as Revenue-Based Liquidity, invoice discounting, purchase order liquidity and short-term working capital. Eligibility, costs and repayment structures vary by provider and facility. 

    2. What is non-dilutive funding? 

    Non-dilutive funding provides capital without requiring a business to sell ownership shares. However, the business still has to meet the agreed financing obligations. 

    3. Is revenue-based financing the same as a traditional business loan? 

    Not necessarily. Revenue-based financing generally links repayment to the business’s revenue or sales structure, while traditional loans typically follow a predetermined repayment schedule. The exact structure depends on the provider and facility. 

    4. Who can qualify for Revenue-Based Liquidity with Fincobox? 

    Fincobox states that MSMEs, D2C and e-commerce businesses with at least six months of operating history and AED 100,000+ in monthly revenue typically qualify, subject to assessment. 

    5. How much can I access through Fincobox Revenue-Based Liquidity? 

    Fincobox states that eligible businesses may access capital of up to 2.5–3 times their monthly revenue, subject to credit assessment and applicable terms. This should not be treated as a guaranteed funding amount. 

    6. What is invoice discounting in the UAE? 

    Invoice discounting allows an eligible business to access liquidity against outstanding invoices instead of waiting until customers complete their payment cycle. Fincobox currently states that eligible businesses can access up to 90% of invoice value, subject to assessment and applicable terms. 

    7. Does Fincobox require businesses to give up equity? 

    No. Fincobox states that its liquidity solutions are non-dilutive, meaning businesses retain ownership of their company. 

    8. How do I choose the right business financing option? 

    Start with the source of the cash-flow gap. Unpaid invoices may point towards invoice discounting; consistent revenue and a growth opportunity may make Revenue-Based Liquidity relevant; and a confirmed customer order may point towards Purchase Order Liquidity. 

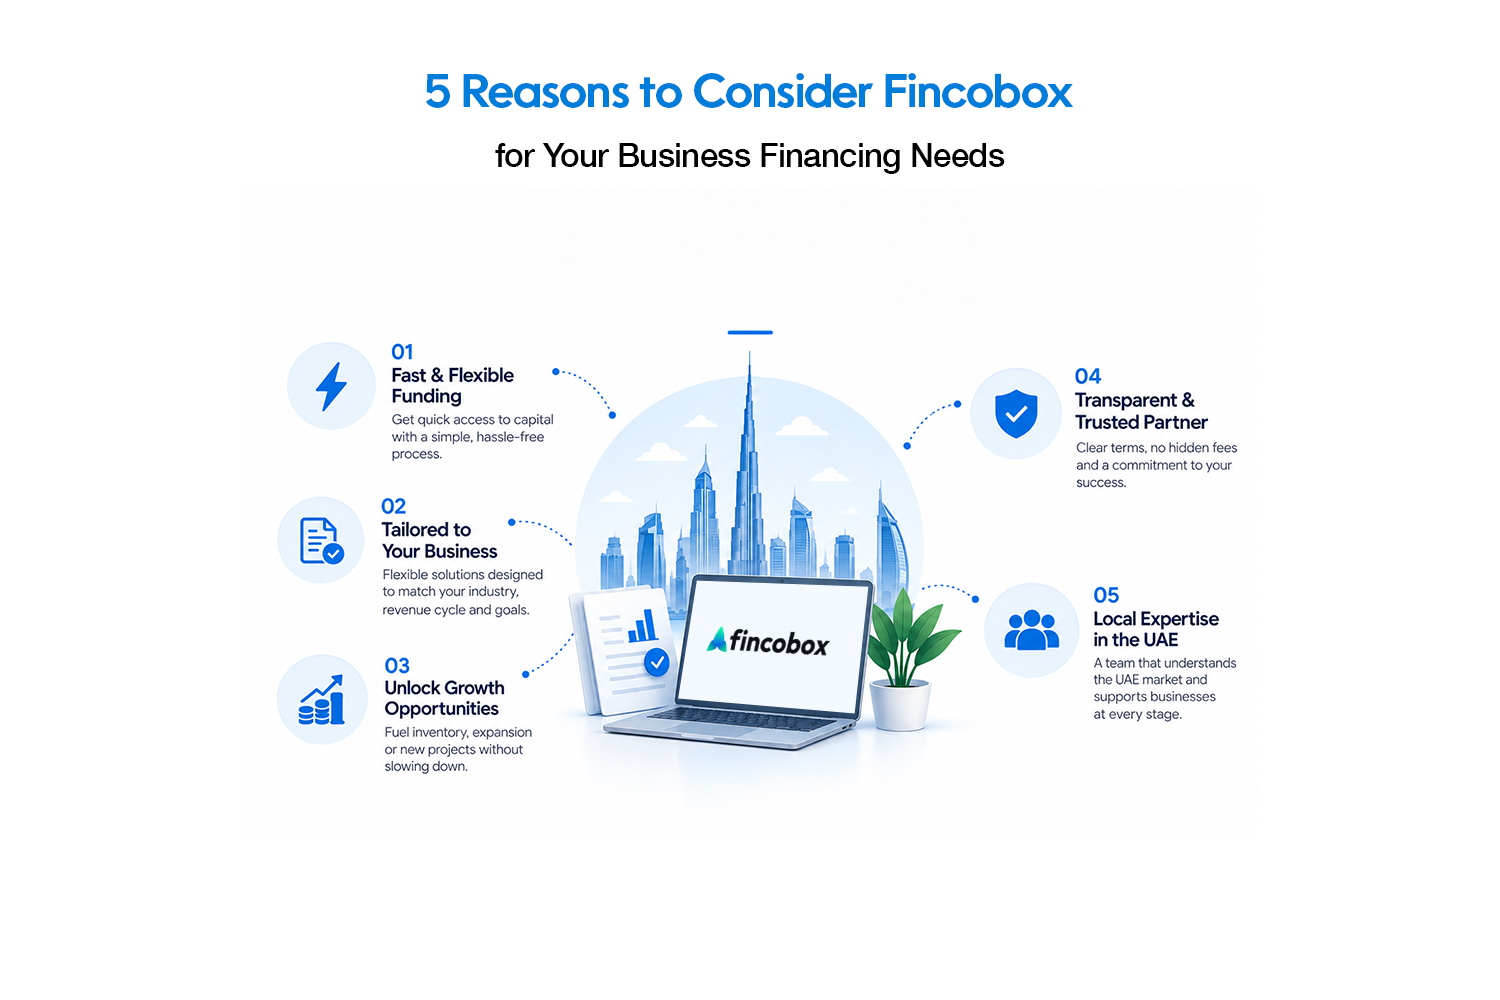
  • 5 Reasons to Consider Fincobox for Your Business Financing Needs

    5 Reasons to Consider Fincobox for Your Business Financing Needs

    Getting access to capital is not always about keeping a business afloat. Sometimes, your business is doing well you have customers, sales and opportunities but your cash flow simply cannot move as quickly as your growth plans. Maybe a major customer has not paid an invoice yet. Maybe you need to purchase inventory before your next sales cycle. Maybe a large order has landed but fulfilling it requires cash up front. Or perhaps you want to invest more in marketing while your revenue is growing. 

    For UAE SMEs, the real question is not simply “Where can I get business financing?” 

    It is: “Which financing solution actually fits the way my business operates?” Here are five reasons businesses may consider Fincobox for their financing needs. 

    1. You Can Choose Financing Based on Your Business Need 

    Not every cash-flow problem is the same. A business waiting 60 days for a customer to pay has a very different financing requirement from an e-commerce company that needs additional inventory or a distributor trying to fulfil a large purchase order. 

    Fincobox takes a use-case-first approach with four main liquidity solutions: 

    • Invoice Discounting – for eligible businesses with outstanding invoices 
    • Revenue-Based Liquidity – for businesses with consistent revenue 
    • Short-Term Working Capital – for operational liquidity requirements 
    • Purchase Order Liquidity – for eligible businesses that need funding to fulfil purchase orders 

    That distinction matters. Instead of starting with a generic loan amount, businesses can first identify what is creating the cash-flow gap and then explore the financing option that corresponds to it. 

    Which Fincobox solution could fit your situation? 

    Your business situation Potential Fincobox solution 
    Cash is tied up in unpaid invoices Invoice Discounting 
    Consistent revenue and a growth opportunity Revenue-Based Liquidity 
    Temporary operating cash requirement Short-Term Working Capital 
    Large order requiring upfront fulfilment costs Purchase Order Liquidity 

    The appropriate product, eligibility and terms will depend on the individual business and assessment. 

    2. Fincobox Financing Is Non-Dilutive 

    For many founders, getting capital creates another concern: 

    “How much of my business do I have to give away?” 

    With equity financing, raising capital means giving investors an ownership stake in the company. Fincobox takes a different approach. Its liquidity solutions are positioned as non-dilutive, meaning eligible businesses can access financing without selling equity or giving up ownership of their company. This can be particularly relevant for founders who want to maintain control while accessing working capital for growth. For example, a growing D2C brand may want additional capital to increase inventory or marketing spend without bringing an investor into the business simply to fund a short-term requirement. 

    However, non-dilutive does not mean cost-free. Businesses should always review the applicable financing costs, fees, repayment or settlement mechanics and contractual terms before accepting an offer. 

    3. It Is Built Around UAE SME Cash-Flow Challenges 

    Business financing should make sense for the market it serves. Fincobox is focused on UAE SMEs, with solutions designed around common working-capital situations such as unpaid invoices, growing revenue, purchase orders and short-term operational requirements. This is particularly relevant as UAE SMEs continue to focus heavily on growth. According to Mastercard’s 2026 SME Confidence Index, 83% of UAE SMEs surveyed reported revenue growth over the previous 12 months, while 50% said they were seeking access to credit to support growth. That highlights an important point: Businesses do not always need financing because they are struggling. Sometimes they need financing because they have an opportunity to grow faster than their available cash allows. 

    4. You Can Unlock Working Capital Without Waiting for the Entire Cash Cycle 

    Cash flow timing can create a frustrating situation for a growing business. 

    • You make the sale today. 
    • You deliver the product or service. 
    • You issue the invoice. 
    • And then you wait. 

    If your customer pays after 30, 60 or 90 days, the cash generated by that sale is temporarily unavailable for your next business requirement. Fincobox’s Invoice Discounting solution is designed to help eligible businesses unlock liquidity against qualifying invoices. Fincobox states that eligible businesses can access up to 90% of invoice value, subject to assessment and applicable terms. 

    For a business with significant receivables, this can potentially turn outstanding invoices into usable working capital sooner. That capital could then be used for business needs such as: 

    • Paying suppliers 
    • Purchasing inventory 
    • Managing operating expenses 
    • Fulfilling new orders 
    • Supporting expansion 

    The key is that invoice discounting addresses a timing problem: money has already been earned but has not yet been collected. 

    5. Fincobox Gives Growing Businesses More Than One Financing Route 

    Your business will not have the same financing requirement at every stage. Today, your biggest issue might be unpaid invoices. Next quarter, you might need capital to purchase inventory. Later, a major customer order could create a need for purchase-order liquidity. That is why having access to different financing solutions can be valuable. Fincobox offers multiple liquidity products within one platform, including invoice discounting, revenue-based liquidity, short-term working capital and purchase order liquidity. For a growing UAE SME, this creates an opportunity to think about financing according to the cash-flow event, rather than treating every requirement as a traditional business loan. 

    What Makes Fincobox Different From Traditional Business Financing? 

    Traditional financing can still be appropriate for many businesses. But it may not always match the timing or structure of a particular working-capital requirement. Fincobox focuses on liquidity solutions connected to specific business circumstances. 

    For example: 

    Unpaid invoice → Invoice Discounting 

    Consistent revenue → Revenue-Based Liquidity 

    Large purchase order → Purchase Order Liquidity 

    Short-term cash requirement → Working Capital 

    This approach can make the financing conversation more practical: 

    What does your business need the money for? 

    rather than simply: 

    How much money do you want to borrow? 

    Who Should Consider Fincobox? 

    Fincobox may be worth exploring if you are a UAE SME that: 

    • Has a clear working-capital requirement 
    • Has outstanding eligible invoices 
    • Generates consistent revenue 
    • Needs capital to support growth 
    • Has received a qualifying purchase order 
    • Wants non-dilutive financing 
    • Needs a financing solution aligned with a specific cash-flow situation 

    Eligibility is not automatic. Businesses are assessed based on the relevant product, business information, financial performance and applicable criteria. 

    What Should You Check Before Choosing Fincobox? 

    Choosing a financing provider should never be based on speed or convenience alone. Before accepting any financing offer, understand: 

    1. The total cost 

    Know what the financing will cost your business. 

    2. The repayment or settlement structure 

    Understand exactly how and when the facility needs to be settled. 

    3. The financing period 

    Make sure the duration matches your actual cash-flow cycle. 

    4. The funding purpose 

    Be clear about what the capital will achieve. 

    5. Your ability to repay 

    Consider what happens if sales are lower or customer payments are delayed Fincobox itself notes that businesses should understand total financing costs and repayment or settlement mechanics when evaluating digital-first financing. 

    Final Thoughts 

    The best business financing is not necessarily the financing with the biggest limit or the quickest application. It is the financing that fits the problem your business is actually trying to solve. For one UAE SME, that might mean unlocking cash from unpaid invoices. For another, it could mean funding inventory based on consistent revenue. For another, it could mean fulfilling a large purchase order without putting pressure on existing cash reserves. Fincobox gives eligible UAE SMEs access to multiple non-dilutive business financing solutions, allowing businesses to explore different ways of addressing working-capital and growth requirements. If your business has a specific cash-flow requirement, the first step is simple: Identify the gap. Understand the cost. Choose the financing structure that fits. 

    Frequently Asked Questions 

    1. What is Fincobox? 

    Fincobox is a UAE-focused digital financing platform that provides non-dilutive liquidity solutions for eligible SMEs, including invoice discounting, revenue-based liquidity, short-term working capital and purchase order liquidity. 

    2. What types of business financing does Fincobox offer? 

    Fincobox currently lists four key liquidity solutions: Invoice Discounting, Revenue-Based Liquidity, Short-Term Working Capital and Purchase Order Liquidity. 

    3. Is Fincobox financing available to UAE SMEs? 

    Yes. Fincobox is specifically focused on providing liquidity solutions to UAE SMEs. Eligibility depends on the business, financing product and assessment criteria. 

    4. Does Fincobox require businesses to give up equity? 

    Fincobox describes its liquidity solutions as non-dilutive, meaning businesses do not need to sell equity or ownership to access the financing. 

    5. How much can I get through Fincobox? 

    The available financing amount depends on the business, product and credit assessment. Fincobox’s website currently displays an estimated overall credit range of AED 50,000 to AED 2 million, while noting that final limits depend on credit evaluation. 

    6. Can Fincobox help if my cash is stuck in unpaid invoices? 

    Yes. Fincobox offers Invoice Discounting for eligible businesses and states that businesses can access up to 90% of eligible invoice value, subject to assessment and applicable terms. 

    7. Is Fincobox suitable for growing businesses? 

    It can be, particularly where a business has a defined working-capital or growth requirement. Fincobox offers different liquidity solutions for situations including consistent revenue, unpaid invoices, purchase orders and short-term working-capital needs. 

    8. What should I consider before applying for Fincobox financing? 

    Consider your exact funding requirement, total financing cost, applicable fees, repayment or settlement structure, financing period and ability to meet the obligations. Financing should support a clear business objective rather than simply increase available cash. 

  • Do You Actually Need Business Financing? 7 Questions to Ask First

    Do You Actually Need Business Financing? 7 Questions to Ask First

    Your business is growing, but your cash balance doesn’t always tell the same story. You may have more customers, larger orders and stronger sales than ever, yet still find yourself wondering whether there is enough cash to pay suppliers, purchase inventory, fund marketing or take on your next opportunity. That is when business financing starts to look attractive. But here is the question many business owners skip: 

    Do you actually need financing or do you need to fix a cash-flow problem first? 

    For UAE SMEs, the answer depends on why you need the money, how quickly you need it and whether the funding will create enough business value to justify its cost. Before applying for business financing in the UAE, ask yourself these seven questions. 

    1. What exactly do I need the money for? 

    Start with the problem, not the financial product. Are you short of cash because: 

    • Customers are taking 60 or 90 days to pay? 
    • You need to purchase inventory before a busy season? 
    • You have received a large purchase order? 
    • You want to increase marketing spend? 
    • You need to cover a temporary working-capital gap? 
    • You are expanding into a new market? 
    • Your business is consistently spending more than it earns? 

    These are very different situations. For example, a business waiting for customers to pay may need invoice discounting, while an e-commerce business with consistent revenue may consider revenue-based liquidity. The right business financing solution starts by identifying the reason behind the cash requirement. 

    2. Is the problem temporary or structural? 

    This may be the most important question on the list. If your business has a temporary cash-flow gap because customers pay later than you need to pay suppliers, financing could potentially bridge that timing difference. But if your business consistently loses money, financing may simply delay the underlying problem. 

    Before applying, look at your: 

    • Revenue 
    • Gross margins 
    • Operating expenses 
    • Customer payment cycles 
    • Supplier payment terms 
    • Monthly cash flow 

    If the business model is fundamentally healthy but cash arrives at the wrong time, financing can potentially be useful. If the business is structurally unprofitable, however, borrowing more money may not solve the problem. 

    3. Will the financing help me make or save money? 

    Don’t ask only, “How much funding can I get?” 

    Ask: “What will this money do for my business?” 

    Suppose you need AED 150,000 to purchase inventory for products that consistently sell out. If that inventory allows you to generate significantly more revenue, the financing could have a clear commercial purpose. The same applies to a marketing campaign, new customer acquisition opportunity or large confirmed order. On the other hand, using short-term financing to repeatedly cover an operating deficit requires much more careful consideration. A useful rule is: Financing should have a clear job to do. 

    4. Is my cash stuck in invoices? 

    Sometimes, you don’t actually need to borrow money, you need earlier access to money your business has already earned. Imagine your company has completed a AED 200,000 B2B sale and issued an invoice, but the customer will pay in 60 days. Your business may be profitable, but AED 200,000 is still tied up in receivables. This is where invoice discounting can become relevant Fincobox offers invoice discounting for eligible UAE businesses and states that businesses can access up to 90% of eligible invoice value, subject to assessment and applicable terms. Instead of waiting for the entire payment cycle, an eligible business can potentially unlock part of that receivable as working capital. 

    5. Do I need a traditional business loan? 

    Not necessarily. Traditional loans are only one of several business financing options available to UAE SMEs. 

    Depending on your situation, you may consider: 

    Your situation Potential financing option 
    Cash tied up in unpaid invoices Invoice discounting 
    Consistent revenue + growth opportunity Revenue-based liquidity 
    Large confirmed customer order Purchase order liquidity 
    Short-term operating cash gap Short-term working capital 

    Fincobox offers these types of liquidity solutions for eligible UAE SMEs. The important point is that these products are not interchangeable. Your financing choice should match the underlying business need. 

    6. Can my business comfortably support the financing? 

    Getting approved doesn’t automatically mean financing is affordable. Before accepting an offer, understand: 

    • Total financing cost 
    • Fees 
    • Repayment or settlement structure 
    • Financing period 
    • Expected cash inflows 
    • What happens if sales decline 
    • Your expected return from using the capital 

    You should be able to explain exactly how and when the financing will be settled. Fincobox states that every registered SME goes through a credit underwriting process before receiving a detailed offer containing the applicable terms and limits.  That assessment is important because the right amount of financing depends on the individual business not simply on what a company requests. 

    7. Am I financing growth or financing a problem? 

    This is the final reality check. Growth financing can make sense when you have a proven business model and a specific opportunity that requires additional working capital. 

    For example: 

    More inventory → more sales → more revenue. 

    Or: 

    Larger order → financing for fulfilment → completed order → customer payment. 

    But if the cycle looks more like: Losses → financing → more losses → more financing, then the issue is probably bigger than a temporary cash-flow gap. Financing should support a healthy business strategy, not replace one. 

    How Much Business Financing Do UAE SMEs Actually Need? 

    There is no universal amount. A small business may need AED 50,000 to bridge an inventory cycle, while another company may require several hundred thousand dirhams to fulfil a major order or expand. The right amount should be based on: Funding requirement + timing + repayment capacity + expected business return. This is particularly important because taking more financing than you need can increase your overall financing cost. 

    UAE SMEs Are Still Focused on Growth 

    The demand for funding is closely connected to the growth ambitions of UAE businesses. According to Mastercard’s 2026 SME Confidence Index, 83% of UAE SMEs surveyed reported revenue growth over the previous 12 months, while 50% said they were seeking access to credit to support growth. (Mastercard) 

    The takeaway is important: financing isn’t necessarily about keeping a struggling business alive. For many SMEs, access to capital is also about having the resources to pursue growth opportunities. 

    Where Does Fincobox Fit In? 

    Fincobox provides non-dilutive liquidity solutions for eligible UAE SMEs, including invoice discounting, revenue-based liquidity, short-term working capital and purchase order liquidity.  The advantage of approaching financing this way is that you can start with your business problem. 

    Unpaid invoice? Explore invoice discounting. 

    Consistent revenue and a growth opportunity? Consider revenue-based liquidity. 

    Large customer order? Look at purchase order liquidity. 

    Temporary operating gap? Short-term working capital may be more relevant. 

    Fincobox also states that its liquidity is non-dilutive, meaning businesses retain ownership and control rather than giving up equity for funding.  

    So, Do You Actually Need Business Financing? 

    Before you apply, ask yourself these seven questions: 

    1. What exactly do I need the money for? 
    1. Is my cash-flow problem temporary or structural? 
    1. Will the financing help me make or save money? 
    1. Is my cash already tied up in invoices? 
    1. Do I really need a traditional business loan? 
    1. Can my business comfortably support the financing? 
    1. Am I financing growth or financing a problem? 

    If you have clear answers, you are in a much stronger position to decide whether financing makes sense and which type may fit your business. For UAE SMEs, the goal shouldn’t simply be to get business financing. It should be to get the right financing for the right business need at the right time. And if your business has a specific working-capital or growth requirement, Fincobox gives eligible UAE SMEs multiple liquidity options to explore based on their circumstances. 

    Frequently Asked Questions 

    1. When does a business actually need financing? 

    A business may need financing when it has a temporary working-capital gap, an opportunity for profitable growth, unpaid invoices tying up cash, inventory requirements or a large order that requires upfront expenditure. 

    2. Is business financing the same as a business loan? 

    No. A traditional business loan is only one type of business financing. SMEs can also explore solutions such as invoice discounting, revenue-based liquidity, purchase order financing and other working-capital facilities. 

    3. What is the best business financing option for an SME in the UAE? 

    There is no single best option. It depends on why the business needs capital. For example, invoice discounting may suit a company waiting for customer payments, while revenue-based liquidity may be relevant to a business with consistent revenue and a growth opportunity. 

    4. Can I get business financing without giving up equity? 

    Some financing structures are non-dilutive, meaning the business does not have to sell ownership to receive capital. Fincobox states that its liquidity solutions are 100% non-dilutive.  

    5. How much business financing should I apply for? 

    You should generally base the amount on your specific funding requirement, expected cash inflows, repayment capacity and the commercial return you expect from using the capital. Avoid taking more financing than your business can reasonably deploy and support. 

    6. Does Fincobox offer different business financing solutions? 

    Yes. Fincobox offers invoice discounting, revenue-based liquidity, short-term working capital and purchase order liquidity for eligible UAE SMEs.  

    7. Is Fincobox business financing available to UAE SMEs? 

    Fincobox is a UAE-focused digital platform offering non-dilutive working-capital solutions to SMEs. Its stated eligibility criteria include MSMEs, D2C and e-commerce businesses with 6+ months of operating history and AED 100,000+ in monthly revenue, subject to assessment. (Fincobox) 

    8. What should I check before accepting business financing? 

    Review the total cost, fees, repayment or settlement structure, financing period, cash-flow impact and your expected return from using the funds. You should also make sure the financing actually addresses the underlying business need. 

  • How to Get Started with Revenue Based Financing with Fincobox?

    How to Get Started with Revenue Based Financing with Fincobox?

    Your business is growing. Sales are coming in, customers are buying, and new opportunities are emerging. But growth often requires cash before it generates more cash. You may need to purchase inventory, increase your marketing budget, launch a new product, or expand operations. Waiting for future sales to arrive could mean missing the opportunity today. This is where Revenue Based Financing (RBF) can be worth exploring. For UAE SMEs with established revenue, Revenue Based Financing provides a way to access capital without giving up ownership of the business. Instead of relying solely on a traditional loan structure, the financing is designed around the business’s revenue and sales performance. 

    What Is Revenue Based Financing? 

    Revenue Based Financing is a form of business financing where a company receives capital upfront and repays it through an agreed structure linked to future revenue. 

    The concept is straightforward: 

    Get capital today → use it to grow → repay through future business revenue This approach can be relevant for businesses with consistent sales that need working capital for a specific growth opportunity. For example, imagine an e-commerce business generating AED 200,000 in monthly revenue but needing additional capital to purchase inventory ahead of a high-demand period. Revenue Based Financing may help bridge that working-capital gap without requiring the founders to sell equity in the company. 

    Why Are UAE Businesses Exploring Alternative Financing? 

    Access to capital remains an important consideration for UAE SMEs. According to Mastercard’s 2026 SME Confidence Index, half of the UAE SMEs surveyed said they are seeking access to credit to support growth, while 37% of business decision-makers identified easier access to funding and financial support as a priority. The takeaway is important: businesses may seek financing not only when they are struggling, but also when they want to invest in growth opportunities. Revenue Based Financing is one option for businesses that already have the revenue profile needed to support this type of facility. 

    How Does Revenue Based Financing Work? 

    Revenue Based Financing can be understood in four simple stages. 

    1. Your Business Generates Revenue 

    Revenue Based Financing is generally designed for businesses with an established revenue stream. Your sales history helps the financing provider assess business performance and repayment capacity. 

    2. You Apply for Funding 

    You provide relevant business and financial information for assessment. This may include: 

    • Monthly revenue 
    • Business operations 
    • Company registration 
    • Business-owner information 
    • Sales channels 
    • Financial performance 

    The exact requirements vary by provider. 

    3. You Receive a Financing Offer 

    After reviewing your business information, the provider determines whether you qualify and, if so, the financing amount and terms available to you. At Fincobox, registered SMEs undergo a credit underwriting process before receiving an offer with the applicable terms and limits. 

    4. Repayment Follows the Financing Structure 

    Revenue-based structures connect repayment to the business’s revenue or sales flows, depending on the facility. For online merchants, Fincobox states that repayments happen automatically through sales and settlement flows. 

    How to Get Started with Revenue Based Financing with Fincobox 

    If you are considering Revenue Based Financing UAE, the process starts with understanding your funding requirement and whether your business fits the financing criteria. 

    Step 1: Identify Why You Need the Capital 

    Start with the business problem, not the funding amount. 

    You may need capital for: 

    Inventory: Purchase additional stock ahead of increased demand. 

    Marketing: Increase customer acquisition spending when you have a clear opportunity to grow sales. 

    Product expansion: Launch a new product or expand your existing range. 

    Business growth: Increase capacity, reach new customers, or enter new markets. 

    Having a clear use for the capital can help you determine whether Revenue Based Financing is appropriate. 

    Step 2: Review Your Revenue 

    Revenue is central to this type of financing. 

    Look at your recent sales and consider: 

    • Is your revenue relatively consistent? 
    • Are your sales growing? 
    • Do you have predictable settlement cycles? 
    • Can the additional capital generate enough value to justify its cost? 

    Understanding your cash flow can help you make a more informed financing decision. 

    Step 3: Check Your Eligibility 

    Fincobox states that MSMEs, D2C and e-commerce businesses with 6+ months of operating history and AED 100,000+ in monthly revenue typically qualify, subject to assessment. 

    These criteria provide a useful starting point, but meeting them does not guarantee approval or a specific funding amount. Fincobox assesses each business before making an offer. 

    Step 4: Prepare Your Business Information 

    Fincobox states that applicants need basic documents related to: 

    • Business-owner KYC 
    • Company registration 
    • Business operational data 

    Preparing these details in advance can help keep the application process straightforward. 

    Step 5: Apply Through Fincobox 

    Once your information is ready, you can register and submit your application through Fincobox. The platform evaluates your business performance and determines the financing terms and limits available to you. Fincobox describes its liquidity solutions as 100% non-dilutive, meaning businesses do not have to give up equity or ownership to access the facility. 

    Step 6: Review the Offer Carefully 

    Receiving an offer is only part of the decision. 

    Before accepting any financing facility, consider: 

    • Total cost of financing 
    • Processing fees 
    • Repayment structure 
    • Financing period 
    • Available amount 
    • Expected revenue 
    • Intended use of funds 

    The objective is not simply to secure capital. It is to choose financing that fits your business’s cash flow and growth plans. 

    How Much Revenue Based Financing Can You Get With Fincobox? 

    The amount available depends on your business and its financial profile. Fincobox states that businesses using its Revenue Based Liquidity can access capital of up to 2.5–3 times their monthly revenue, with repayment terms that can vary between 6 and 9 months. These figures are subject to credit assessment and the applicable terms of the facility. For example, a business generating AED 200,000 in monthly revenue may be assessed for a larger facility than a business generating AED 50,000. However, the revenue multiple should not be treated as a guaranteed funding amount. The final facility depends on the individual business assessment and the terms offered. 

    What Can You Use Revenue Based Financing For? 

    Revenue Based Financing can be useful when capital is needed to support activities that are expected to contribute to future business revenue. 

    Common applications include: 

    Inventory 

    Purchase additional stock before a high-demand period instead of waiting for cash reserves to build. 

    Marketing 

    Increase marketing investment when there is a clear opportunity to acquire more customers and generate additional sales. 

    Product Expansion 

    Launch new products or expand an existing product range. 

    Business Growth 

    Fund initiatives that help increase capacity, reach new customers, or enter new markets. Fincobox specifically positions its Revenue Based Liquidity for businesses with consistent online sales that need funding for marketing, product expansion, or inventory needs. 

    Revenue Based Financing vs Traditional Business Loans 

    The key difference is how the financing is structured. A traditional business loan typically comes with a predetermined repayment schedule. Revenue Based Financing, by comparison, is structured around the business’s revenue or sales performance, depending on the facility. 

    Neither option is automatically better. The right choice depends on factors such as: 

    • Revenue consistency 
    • Growth plans 
    • Funding requirement 
    • Cash-flow cycle 
    • Financing cost 
    • Repayment capacity 

    Businesses should compare the total cost and obligations of each option before making a decision. 

    Why Consider Fincobox for Revenue Based Financing in the UAE? 

    Fincobox is a digital platform offering non-dilutive liquidity solutions for UAE SMEs. Its current product range includes: 

    • Revenue Based Liquidity 
    • Invoice Discounting 
    • Short-Term Forfaiting Arrangements 
    • Purchase Order Liquidity 

    Each solution addresses a different working-capital requirement. For example, a business with unpaid invoices may consider invoice discounting, while a business with consistent online revenue that needs capital for inventory or marketing may consider Revenue Based Liquidity. The important point is to identify the underlying cash-flow need first and then evaluate the financing solution that fits it. 

    Is Revenue Based Financing Right for Your Business? 

    Revenue Based Financing may be worth considering if your business: 

    • Has established and relatively consistent revenue 
    • Has been operating for at least the required period 
    • Has a clear growth opportunity 
    • Needs working capital for growth 
    • Wants to avoid equity dilution 
    • Can comfortably manage the applicable repayment structure 

    It may not be suitable for every business. If your company is pre-revenue, has highly unpredictable sales, or does not have a clear use for the capital, another financing option may be more appropriate. 

    The key question is not simply: 

    “Can I get funding?” 

    It is: 

    “Will this funding help my business create enough value to justify its cost?” 

    Final Takeaway 

    For a growing UAE business, waiting for future revenue can sometimes mean waiting too long to act on a valuable opportunity. Revenue Based Financing provides an alternative way for eligible businesses to access capital while retaining ownership. With Fincobox, eligible UAE SMEs can explore Revenue Based Liquidity based on their monthly revenue, with financing positioned for needs such as inventory, marketing, and product expansion. If your business has established revenue and a clear growth opportunity, Revenue Based Financing could be worth considering as part of your broader SME financing strategy in the UAE. 

    Frequently Asked Questions 

    1. What is Revenue Based Financing in the UAE? 

    Revenue Based Financing is a business financing model where capital is provided upfront and repayment is structured around the business’s future revenue or sales, depending on the facility. 

    2. Who is eligible for Revenue Based Financing with Fincobox? 

    Fincobox states that MSMEs, D2C and e-commerce businesses with 6+ months of operating history and AED 100,000+ in monthly revenue typically qualify, subject to assessment. 

    3. How much can I get through Fincobox Revenue Based Liquidity? 

    Fincobox states that businesses can access capital of up to 2.5–3 times their monthly revenue, subject to credit assessment and applicable terms. Repayment terms can vary between 6 and 9 months. 

    4. Do I have to give up equity with Revenue Based Financing? 

    Fincobox states that its liquidity is 100% non-dilutive, meaning businesses do not give up equity or ownership to access the facility. 

    5. What can I use Revenue Based Financing for? 

    Fincobox specifically positions its Revenue Based Liquidity for businesses with consistent online sales that need funding for areas such as marketing, inventory, and product expansion. 

    6. How long does Fincobox Revenue Based Financing take? 

    Fincobox states that its verification process can take 1–2 business days after the required information is submitted. Once the facility is activated, Fincobox says most qualifying businesses receive funds within 7 days of their fund request. Timing can vary depending on the process and applicable terms. 

    7. Is Revenue Based Financing better than a traditional business loan? 

    Not necessarily. The right option depends on your business model, revenue consistency, funding purpose, financing cost, and repayment capacity. 

    8. Can I apply for more than one Fincobox financing solution? 

    Yes. Fincobox states that businesses can apply for both Revenue Based Liquidity and Invoice Discounting simultaneously, allowing different facilities to address different working-capital requirements. 

  • What Documents Do You Need for Invoice Financing?

    What Documents Do You Need for Invoice Financing?

    If your business has completed a sale but your customer has not paid yet, the money may be sitting in your accounts receivable instead of being available for day-to-day use.  Invoice financing can help eligible businesses access working capital against outstanding invoices rather than waiting for the full payment cycle. 

    But what documents do you need to apply? For UAE SMEs considering an invoice discounting solution in the UAE, having the right documents ready can make the assessment process more straightforward and help a financing provider understand your business, customer and underlying transaction. 

    What Is Invoice Financing? 

    Invoice financing is a working capital solution that allows a business to access funds against eligible unpaid invoices.  Instead of waiting 30, 60 or 90 days for a customer to pay, an approved business may receive an advance against the invoice. The facility is then settled according to the agreed terms when the customer payment is received. For UAE SMEs, this can be useful when sales are healthy but cash flow is temporarily tied up in receivables. 

    The advance percentage, fees, repayment structure and eligibility criteria vary by provider and business. 

    What Documents Are Needed for Invoice Financing? 

    The exact requirements depend on the financing provider, your business and the invoices being financed. However, businesses should generally be prepared to provide the following. 

    1. The Invoice You Want to Finance 

    The invoice is one of the most important documents in the application. 

    It should clearly show: 

    • Your business name and details 
    • Customer or buyer details 
    • Invoice number 
    • Invoice amount 
    • Issue date 
    • Payment due date 
    • Agreed payment terms 
    • Description of the goods or services provided 

    The provider uses this information to assess the receivable and determine whether the invoice is eligible for financing. 

    2. Valid UAE Trade Licence 

    A valid UAE trade licence is commonly required to verify that your business is legally registered and operating. 

    Depending on the provider and company structure, you may also need additional corporate documents, such as your Memorandum of Association or other registration records. 

    3. Recent Business Bank Statements 

    Bank statements give the financing provider visibility into your company’s financial activity and cash flow. 

    You may be asked for several months of corporate bank statements. The exact period varies by provider. For example, Kema’s guidance for UAE SMBs refers to 6–12 months of bank statements as a common requirement. 

    These statements can help providers understand your business activity, incoming payments and overall financial position. 

    4. Purchase Orders, Contracts or Commercial Agreements 

    Supporting documents can help establish the relationship between your business and the customer. 

    Depending on the transaction, these may include: 

    • Purchase orders 
    • Sales contracts 
    • Work orders 
    • Service agreements 
    • Other commercial agreements 

    For example, if your company supplied goods under a purchase order, the PO can help demonstrate what the invoice relates to and support its validity. 

    5. Proof of Delivery or Service Completion 

    Providers may also require evidence that the goods or services linked to the invoice have actually been delivered or completed. 

    This could include: 

    • Delivery notes 
    • Goods received notes 
    • Completion certificates 
    • Service confirmations 
    • Shipping documents 
    • Other proof of fulfilment 

    This documentation is particularly useful because it connects the invoice to a completed commercial transaction. 

    6. Company and KYC Documents 

    You may also need documents that verify the company, its owners and authorised representatives. 

    These can include: 

    • Memorandum of Association (MOA) 
    • Articles of Association, where applicable 
    • Passport copies 
    • Emirates IDs 
    • Shareholder information 
    • Details of authorised signatories 
    • Other KYC or compliance documents 

    The exact requirements depend on the provider and your company’s legal structure. 

    Does Every Invoice Qualify for Invoice Financing? 

    No. Having an unpaid invoice does not automatically mean it can be financed. 

    Providers may assess: 

    • The business issuing the invoice 
    • The customer who owes the money 
    • Invoice value 
    • Payment terms 
    • Whether the goods or services have been delivered 
    • Whether the invoice is disputed 
    • Supporting transaction documents 
    • The overall financial profile of the business 

    In general, clear, verifiable invoices supported by proper commercial documentation are easier to assess. 

    Why Does Documentation Matter? 

    Good documentation helps a provider answer three basic questions: 

    1. Is the business legitimate and financially active? 

    Your trade licence, company documents and bank statements help establish this. 

    2. Is the customer and receivable credible? 

    The invoice, payment terms and customer information provide context around the money owed. 

    3. Did the underlying transaction actually take place? 

    Purchase orders, contracts and delivery or completion evidence help establish this. Preparing these documents in advance can reduce unnecessary back-and-forth and make the application process more efficient. 

    How Fincobox Can Help UAE SMEs 

    For businesses with cash tied up in outstanding invoices, the benefit of invoice discounting is simple: you can potentially access working capital before your customer pays. Fincobox provides digital-first liquidity solutions for UAE businesses, including Invoice Discounting. Its website states that eligible businesses can access up to 90% of invoice value within 24 hours, subject to assessment and applicable terms. Fincobox also states that its liquidity solutions require no collateral. 

    For an SME, access to that liquidity can help with practical needs such as: 

    • Paying suppliers on time 
    • Managing payroll and operating expenses 
    • Replenishing inventory 
    • Fulfilling new orders 
    • Taking advantage of growth opportunities 
    • Bridging short-term cash-flow gaps 

    Instead of allowing an outstanding invoice to keep working capital locked up, businesses can potentially put that receivable to work sooner. Fincobox also uses a digital-first process, helping businesses submit information and documents for assessment without relying on a lengthy traditional financing process. 

    As with any financing facility, the amount available, approval and terms depend on the business, invoice and assessment. 

    A Simple Invoice Financing Document Checklist 

    Before applying, it can help to have these documents ready: 

    • ✅ Valid UAE trade licence 
    • ✅ Invoice or invoices you want to finance 
    • ✅ Recent corporate bank statements 
    • ✅ Purchase order or customer contract, where applicable 
    • ✅ Proof of delivery or service completion 
    • ✅ Company registration documents 
    • ✅ Identification documents for relevant owners or authorised signatories 
    • ✅ Any additional customer or transaction information requested by the provider 

    The better organised your records are, the easier it can be for a provider to understand the business and the receivables being financed. 

    Final Thoughts 

    Invoice financing can help UAE SMEs access working capital tied up in eligible outstanding invoices instead of waiting for the full customer payment cycle. While requirements vary between providers, businesses should generally be prepared with their trade licence, invoices, bank statements and supporting transaction documents.  If your business regularly waits weeks or months for customers to pay, an invoice discounting solution in the UAE could be worth exploring as part of your working capital strategy.  Fincobox offers invoice discounting and other invoice financing solutions designed to help eligible UAE businesses improve liquidity and manage cash-flow gaps. Its current website states that businesses may access up to 90% of eligible invoice value within 24 hours, with no collateral required, subject to assessment and applicable terms. 

    Frequently Asked Questions 

    1. What documents are required for invoice financing? 

    Common documents include a valid UAE trade licence, invoices to be financed, recent business bank statements, purchase orders or contracts, proof of delivery or service completion, and company or KYC documents. Requirements vary by provider. 

    2. Do I need a trade licence for invoice financing in the UAE? 

    Typically, UAE businesses need to provide valid company registration or trade licence documentation as part of the verification process. Specific eligibility requirements depend on the financing provider. 

    3. Can I finance an unpaid invoice? 

    Potentially, yes. Eligible unpaid invoices can be considered for invoice financing, subject to assessment of the business, customer, transaction and invoice terms. 

    4. Is invoice financing the same as invoice discounting? 

    Invoice financing is a broader term for solutions that provide funding against outstanding receivables. Invoice discounting is one type of invoice financing arrangement. The exact structure, fees and repayment terms depend on the provider. 

    5. How much of an invoice can I finance with Fincobox? 

    Fincobox states that eligible businesses can access up to 90% of invoice value, subject to assessment and applicable terms. 

    6. How quickly can I receive invoice financing? 

    The timeline depends on the provider, documentation and assessment. Fincobox currently states that eligible businesses can access up to 90% of invoice value within 24 hours, subject to applicable terms. 

    7. Who can use invoice financing in the UAE? 

    Invoice financing may be relevant to businesses that issue invoices on credit terms and have eligible outstanding receivables. SMEs, traders, wholesalers, manufacturers and B2B service businesses may find it useful, subject to provider-specific eligibility criteria. 

  • Can Invoice Financing Help Businesses Accept Larger Orders?

    Can Invoice Financing Help Businesses Accept Larger Orders?

    Yes, but there is an important timing distinction. Invoice financing can help a business after an eligible sale has been completed and an invoice exists. It does not automatically provide the cash needed to fulfil an order before delivery. That difference is critical for SMEs planning to accept larger contracts. 

    The Large-Order Cash Gap 

    Imagine a UAE distributor wins a AED 500,000 customer order. 

    To fulfil it, the distributor needs: 

    • AED 220,000 for inventory 
    • AED 40,000 for logistics 
    • AED 25,000 for temporary labour 

    The customer will pay 60 days after delivery. The business has two different financing needs at two different points: 

    Before delivery: It needs cash to fulfil the order. 

    After invoicing: It may need cash while waiting for the customer to pay. 

    Invoice financing is generally relevant to the second stage. 

    When Invoice Financing Can Help Growth 

    Once the business has delivered and issued an eligible invoice, financing against that receivable may free up cash that can support the next order. 

    For example: 

    1. Order A is delivered. 
    1. The customer receives an invoice with 60-day terms. 
    1. Cash from Order A is still unavailable. 
    1. Order B arrives and requires new inventory. 
    1. Liquidity against an eligible invoice may help the business avoid waiting until day 60 before funding its next operating cycle. 

    This is how invoice financing can support a sequence of larger orders: by reducing the time cash remains locked in receivables. 

    When Invoice Financing Is the Wrong Tool 

    If the business has only a purchase order and has not yet delivered the goods or services, there may be no invoice available to finance. In that case, purchase-order-related funding may be more relevant. 

    Similarly, invoice financing may not solve the problem if: 

    • The order itself has very low margins. 
    • The customer is likely to dispute or delay payment. 
    • The invoice is not eligible. 
    • The cost of financing outweighs the profit from taking the next order. 
    • The business has a long-term capital shortage rather than a short receivables gap. 

    Invoice Financing vs Purchase Order Funding 

    Business stage Potential financing need 
    Purchase order received, goods not yet delivered Purchase-order-related funding may be relevant 
    Goods/services delivered, invoice issued Invoice financing may be relevant 
    Business has consistent revenue and needs growth capital Revenue-based liquidity may be worth evaluating 
    General temporary operating gap Short-term working capital may be relevant 

    The best option depends on where the business is in the sales cycle. 

    A Practical Order-Acceptance Checklist 

    Before accepting a large order, calculate: 

    1. Total upfront cash required. 
    1. Gross profit expected from the order. 
    1. Date suppliers must be paid. 
    1. Date the customer is expected to pay. 
    1. Existing cash available. 
    1. Financing cost for the gap period. 
    1. A contingency if the customer pays late. 

    For example, a AED 500,000 order is not automatically a good growth opportunity. If it requires AED 400,000 upfront, produces a very thin margin and payment is uncertain, financing may increase risk rather than reduce it. 

    Where Fincobox Can Be Relevant 

    Fincobox offers Invoice Discounting for eligible UAE SMEs and states that eligible businesses may access up to 90% of invoice value, subject to assessment and applicable terms. The platform also offers Purchase Order Liquidity, Revenue-Based Liquidity and Short-Term Working Capital. The appropriate option depends on whether the business needs cash before fulfilment, after invoicing, against revenue or for a broader short-term operating requirement. 

    Final Thoughts 

    Invoice financing can help businesses accept larger orders indirectly by improving the cash conversion cycle after sales have been invoiced. The most important decision is timing: Do you need cash to fulfil the current order, or do you need to unlock cash from a completed sale to fund the next one? Those are different problems and may require different financing structures. 

    Frequently Asked Questions 

    1. Can I use invoice financing before delivering an order? 

    Generally, invoice financing is linked to an eligible invoice, so it is typically relevant after the sale has progressed to the invoicing stage. If you need funding before fulfilment, explore whether purchase-order-related financing is available. 

    2. How much of an invoice can be financed? 

    The advance percentage depends on the provider and assessment. Fincobox states that eligible businesses may access up to 90% of eligible invoice value, subject to applicable terms. 

    3. What happens if the customer pays late? 

    The consequences depend on the facility agreement. Ask about extended fees, settlement obligations and the process for late or disputed invoices before accepting financing. 

    4. What documents might I need? 

    Providers may request company information, financial records, the invoice, customer details and supporting evidence relating to the underlying sale or delivery. 

    5. How do I know whether the financing cost is worth it? 

    Compare the total cost of financing with the additional profit or commercial benefit created by accepting or accelerating the next order. If financing merely allows the business to take low-margin or high-risk work, it may not improve the overall financial position.